- Bitmine Immersion Technologies (NYSE: BMNR) is a company whose business is, almost entirely, holding Ethereum. It owns 5,929,198 ETH, or 4.9% of supply, and its market capitalization is about $15.10 billion at a $25.03 share price. This BMNR stock analysis covers how the company got here, how much ETH it holds and how fast it is still buying, whether the stock trades above or below the assets it holds, what share issuance does to existing holders, what chairman Tom Lee and the three covering brokers expect, who owns the shares, how the company compares with buying ETH directly or with Strategy, SharpLink Gaming and Hyperliquid Strategies, and the conditions under which the share price rises or falls.
- The short version: the market capitalization is 0.96 times the $15.7 billion of crypto, cash and venture stakes the company reported in its September 8 weekly filing, a discount of about 4%. While that ratio sits below 1, selling new shares to buy ETH lowers ETH per share for existing holders. For the stock to rise, either the ETH price has to rise or that ratio has to move back above 1, and the last section lists the conditions in a table.
- Two limits first. The share count is the 603.2 million on the cover of the July 9 quarterly report, the last disclosed figure, so market capitalization and per-share holdings are estimates on that basis, while assets are the company's September 7 tally. The article draws on the two investor decks the company posted, all 100 weekly 8-K press releases, the quarterly report, the proxy statement and the 13F holdings tables of 20 well-known investors.
- Over the last month the stock is up 38.4%, over three months 55.4%, and over one year down 47.6%. Ethereum went from a June low of $1,630 back to about $2,500 in those three months. The most recent results are fiscal Q3 2026 (quarter ended May 31, 2026), reported July 14.

What Bitmine Does and How It Got Here
- Bitmine took its name in July 2021 when a shell called Sandy Springs Holdings reverse-merged into it, with founder Jonathan Bates as chairman and CEO. From 2022 it ran immersion-cooled Bitcoin miners in Trinidad and Pecos, Texas. In May 2024 it filed an 8-K (Item 4.02) saying its FY2023 and FY2022 financial statements could not be relied on, and changed auditors. Through May 2025 total assets were $8.26 million and the market capitalization was around $30 million.
- The pivot happened in June 2025. A 1-for-20 reverse split and an NYSE American listing on June 5, a ThinkEquity-led offering on June 10, and on June 30 the election of Fundstrat's Tom Lee as chairman alongside a private placement of 55,555,556 shares at $4.50. The $250 million was funded "in a combination of cash and cryptocurrencies," and on July 8 the company signed an ETH treasury strategy consulting agreement with Ethereum Tower LLC. The source is the June 30, 2025 8-K.
- The year after that was spent growing the treasury. The January 15, 2026 annual meeting raised authorized shares from 500 million to 50 billion; Pier Two, an Australian staking-infrastructure company, was acquired on March 24 to form the MAVAN Holdings subsidiary; auditor Bush & Associates was dismissed on April 27; a preferred stock was sold on June 4; the fiscal year-end was moved from August to December on July 9; and on September 4 the company and Ethereum Tower mutually terminated their staking management agreement. The company has three full-time employees.
| Year | One line | Source |
| 2021 | Shell reverse merger creates Bitmine under founder Bates | 8-K Jul 27, 2021 (5.01, 5.06) |
| 2022 | Immersion mining JV in Trinidad and Texas (ROC Digital) | 8-K Oct 19, 2022 (2.01) |
| 2023 | A $645,000-revenue miner losing $2.46 million | 10-K/A |
| 2024 | Non-reliance on FY2023 and FY2022 statements; auditor change | 8-K May 7, 2024 (4.01, 4.02) |
| 2025 | Reverse split, NYSE American, Tom Lee, $250 million placement, $2 billion ATM | 8-K Jun 10, Jun 30, Jul 9, 2025 |
| 2026 | 50 billion authorized shares, Pier Two, auditor change, preferred, fiscal-year change, MSA termination | 8-K Jan 20, Mar 30, May 1, Jun 5, Jul 13, Sep 8, 2026 |
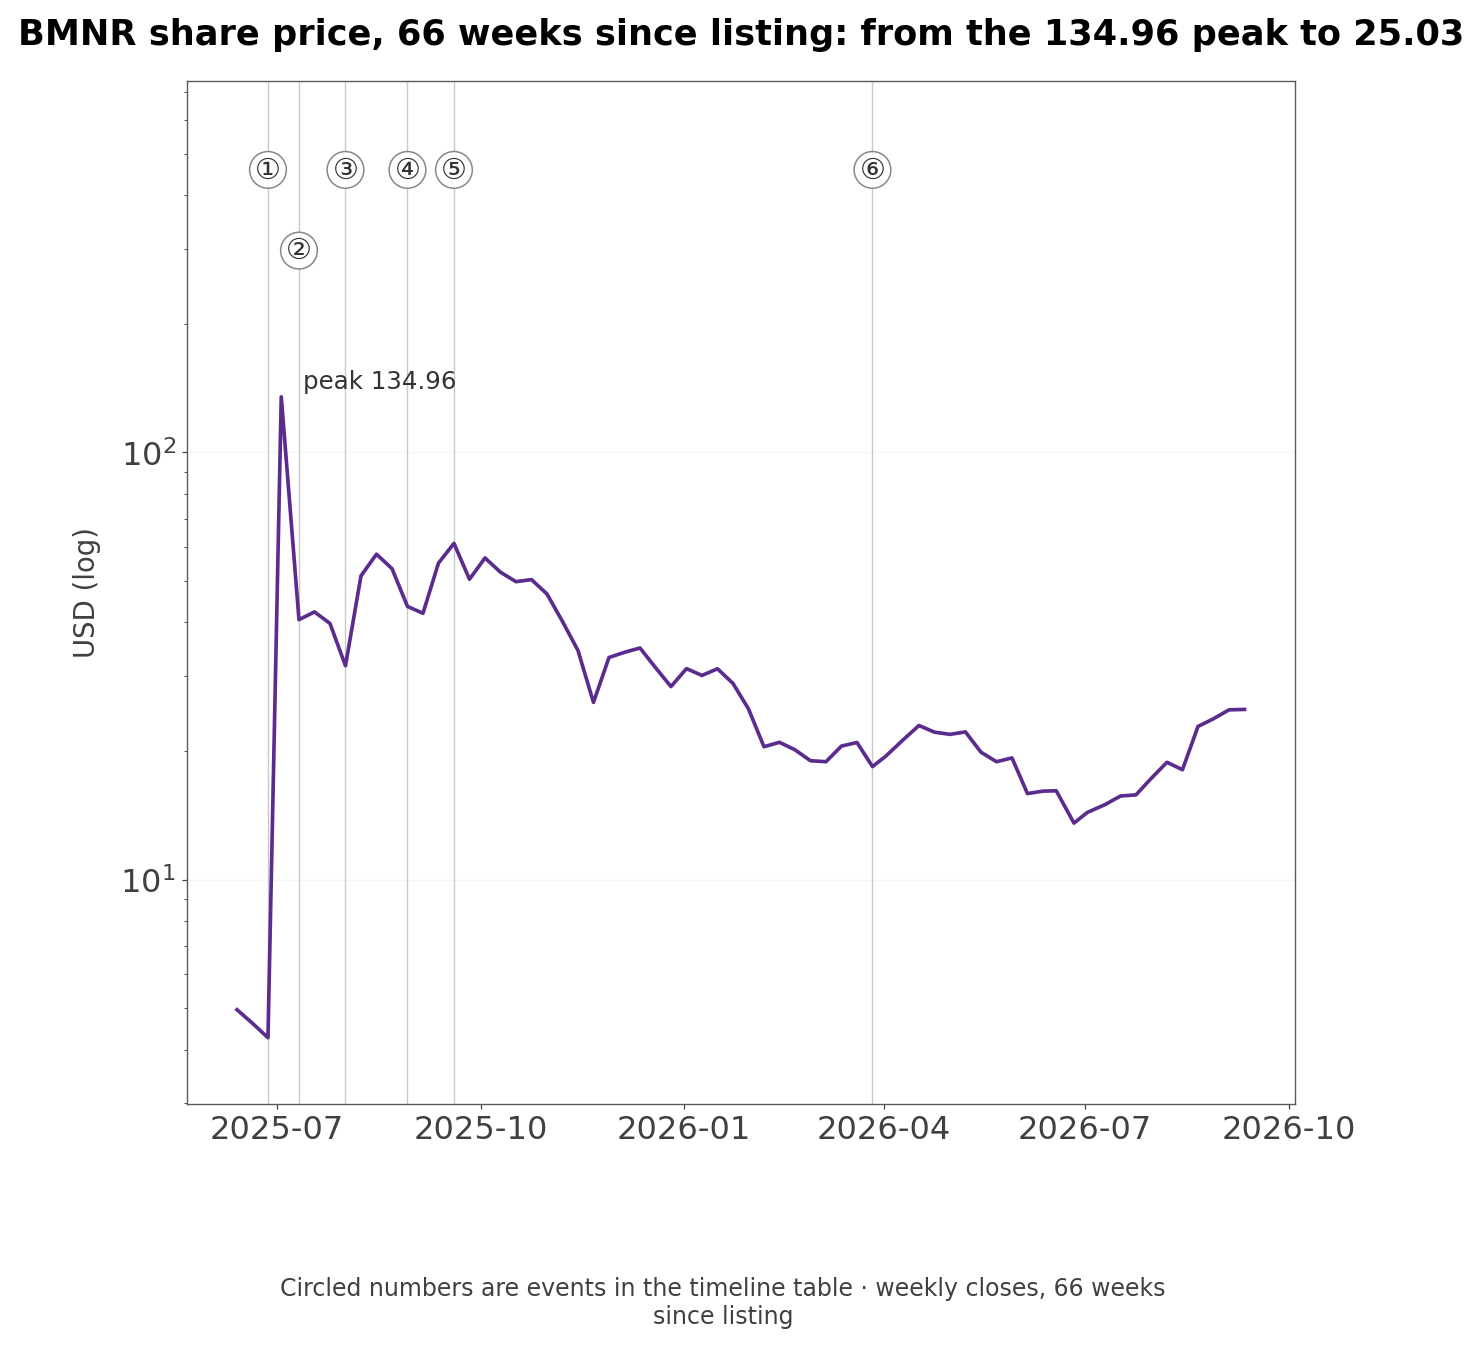
- Own calculation (66 weekly adjusted closes): The weekly high since listing is $134.96 in the week of July 3, 2025, and the low before it is $4.26 in the week of June 27, a multiple of 31.7. At $25.03 the stock is 81.5% below the high and 5.05 times its first week.
- Five fiscal years in one table separate the mining era from the first treasury year. Revenue, operating income and net income are 10-K XBRL values; the debt ratio is total liabilities over equity; ROE is net income over year-end equity.
| Fiscal year-end | Revenue | Operating income | Net income | Operating margin | Net margin | Debt ratio | ROE |
| Aug 2021 | $0 | -$0.13 million | -$0.15 million | n/a | n/a | 79.2% | -42.8% |
| Aug 2022 | $0.43 million | -$1.71 million | -$2.01 million | -400.8% | -468.9% | 7.7% | -27.1% |
| Aug 2023 | $0.65 million | -$2.41 million | -$2.46 million | -374.0% | -382.0% | 31.1% | -39.4% |
| Aug 2024 | $3.31 million | -$2.45 million | -$3.29 million | -73.9% | -99.5% | 78.2% | -80.6% |
| Aug 2025 | $6.10 million | $444.21 million | $348.58 million | 7,288.1% | 5,719.1% | 1.2% | 4.0% |
- An operating margin of 7,288% is not a typo. Ethereum mark-to-market gains run through operating income under the company's accounting, so $6.10 million of revenue carries $444.21 million of operating profit. The only profitable year is the one in which ETH went up; nine months into FY2026 the net loss is $9.11 billion.
- From 318 trading days since listing, the five largest single-day moves all fall inside ten days, June 30 to July 10, 2025.
| Date | Move | Close | Filings within a day | What it was |
| 2025-06-30 | +694.8% | $4.26 to $33.90 | 8-K Items 5.02 and 7.01 (Tom Lee named chairman; $250 million placement at $4.50) | Closed at 7.5x the placement price |
| 2025-07-01 | +35.7% | $33.90 to $46.00 | No filing | Day before the 10-Q |
| 2025-07-03 | +130.8% | $58.50 to $135.00 | 8-K Item 1.01 (placement purchase agreements); 10-Q; 10-Q/A | Shortened pre-holiday session; 30x the placement price |
| 2025-07-09 | -40.2% | $111.50 to $66.72 | 8-K Item 1.01 ($2 billion ATM with Cantor and ThinkEquity); S-3ASR (resale registration for placement shares); 8-K Item 3.02 (Ethereum Tower consulting agreement) | The day 55.6 million shares bought at $4.50 became sellable |
| 2025-07-10 | -31.0% | $66.72 to $46.01 | No filing | 66% below the $135 high |
- On July 9 three filings landed together: the $2 billion at-the-market program with Cantor Fitzgerald and ThinkEquity as sales agents, an automatic shelf that registered the placement shares for resale, and the Ethereum Tower consulting agreement with unregistered shares issued as consideration (July 9, 2025 8-K). Over the next two sessions the stock gave back two thirds of the $135 high. That the filings and the drop share a date is what the record shows; that the filings caused the drop is not something this article can prove. Across the 318 sessions, 134 moved more than 5% in a day, 64 up and 70 down.
Ethereum Holdings and Staking Revenue
Holdings and the Pace of Buying
- The weekly release attached to the September 8 8-K puts holdings at 5,929,198 ETH, 4.9% of a 120.7 million supply. Staked ETH is 5,067,309, or 85.5% of holdings; crypto, cash and venture stakes together are $15.7 billion; cash is $593 million (September 8, 2026 8-K).
- The company has filed a weekly holdings 8-K every Monday since July 2025. I parsed all 100 releases into a time series. Net holdings never fell from one week to the next, and the pile is up 36 times from 163,142 ETH on July 14, 2025. Whether ETH was sold and rebought within a week is not something the data can show.
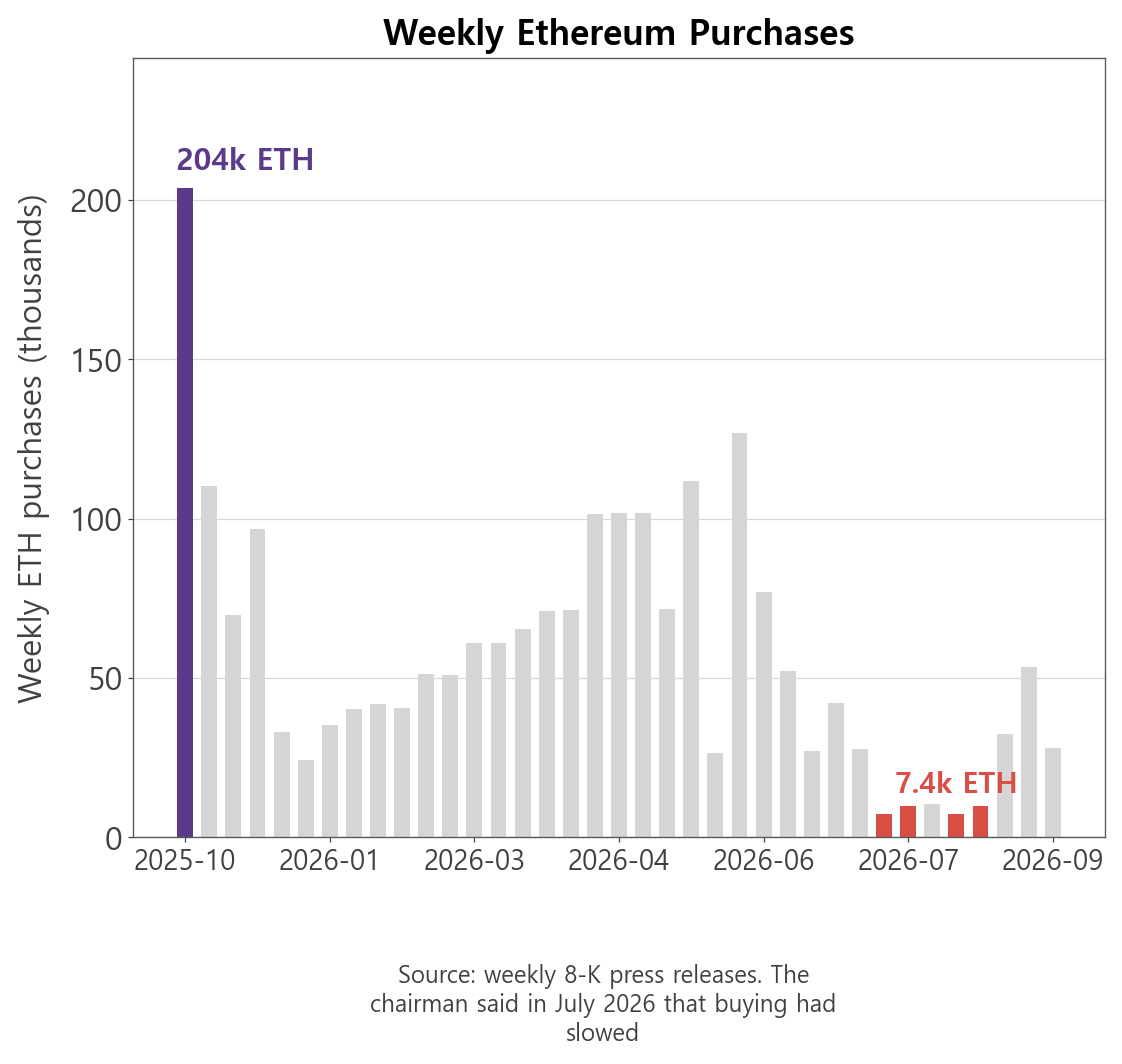
- Own calculation (weekly press releases): Weekly purchases peaked at 203,826 ETH in the week reported October 20, 2025, and fell to 7,391 ETH in the August 10, 2026 release. The September 7 figure is 28,086. The distance to the stated 5% goal is 6,035,000 minus 5,929,198, or 105,802 ETH.
- The trough was one twenty-eighth of the peak, and the latest week is back to about one seventh. At September's pace the 5% goal is four weeks away; at August's pace, fourteen.
- The company said this first. The first of four goals in the July 2026 Chairman's Message is to "slowly reach 5% of the Ethereum supply," and the transcript continues: "We've talked about slowing our buying. Part of it is that the Ethereum Foundation is in transition, they're shrinking their role. And we spoke to many people at the Foundation, and at the moment, I think we shouldn't try to accelerate and have more concentration beyond 5%."
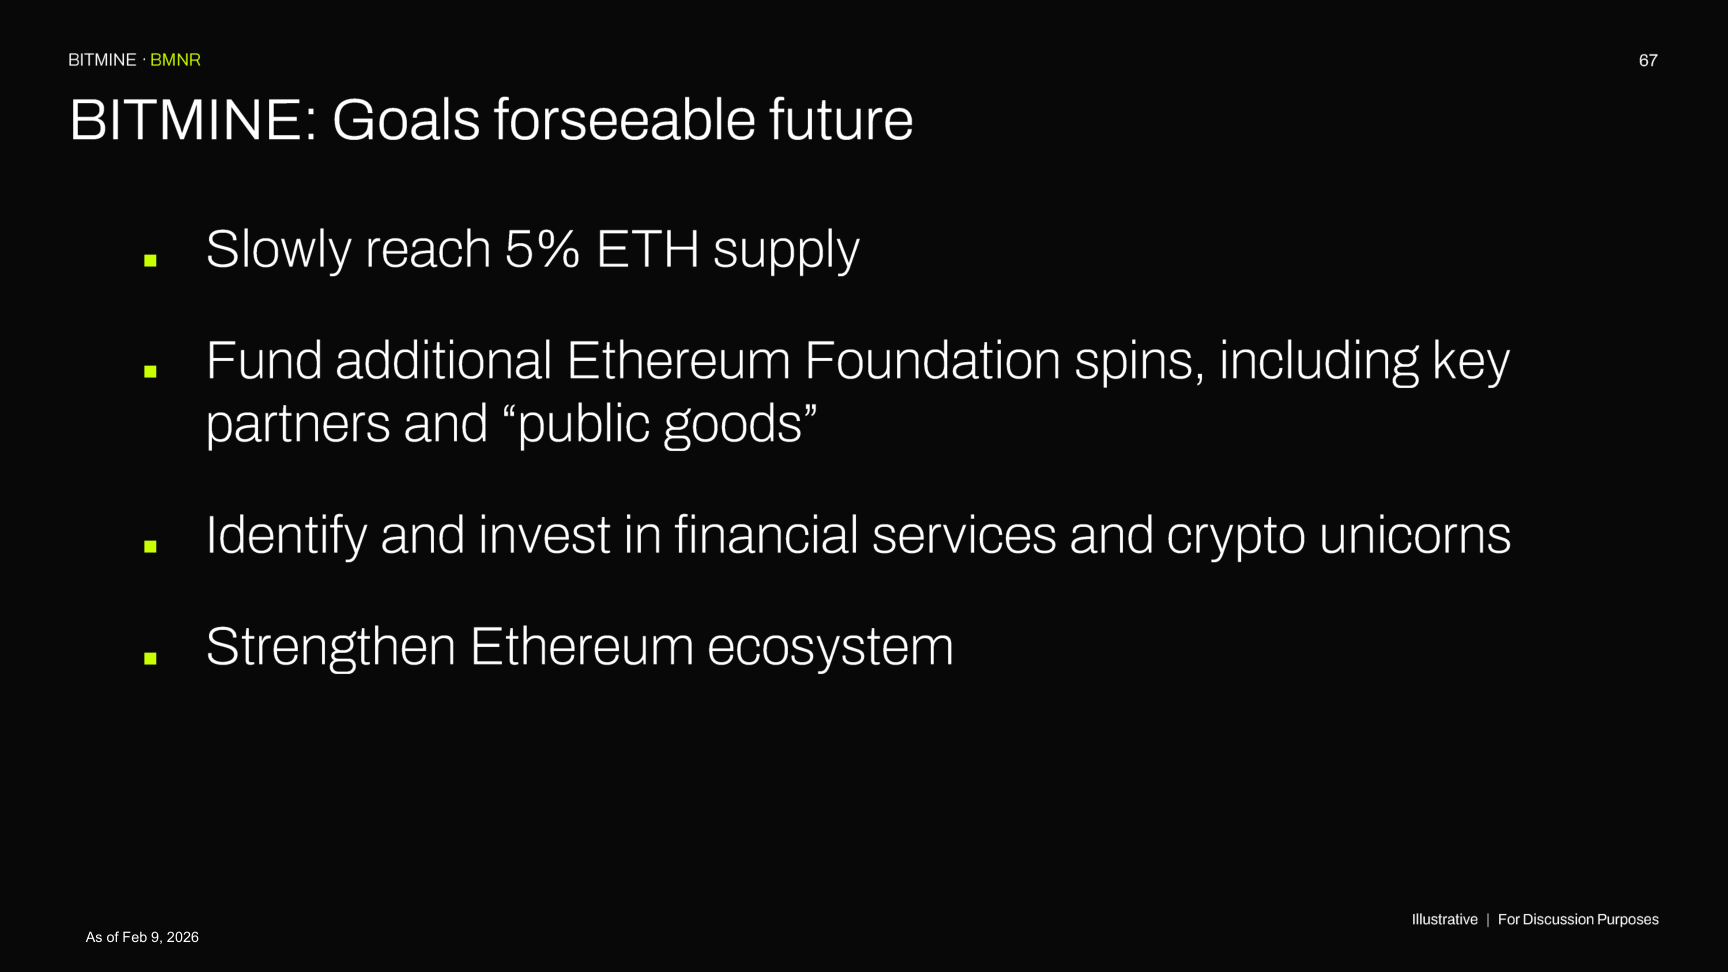
- The other three goals on slide 67 are funding more Ethereum Foundation spin-offs, investing in financial services and crypto unicorns, and strengthening the ecosystem. If buying ETH every week was this company's whole job, the jobs it now describes belong to an investment firm.
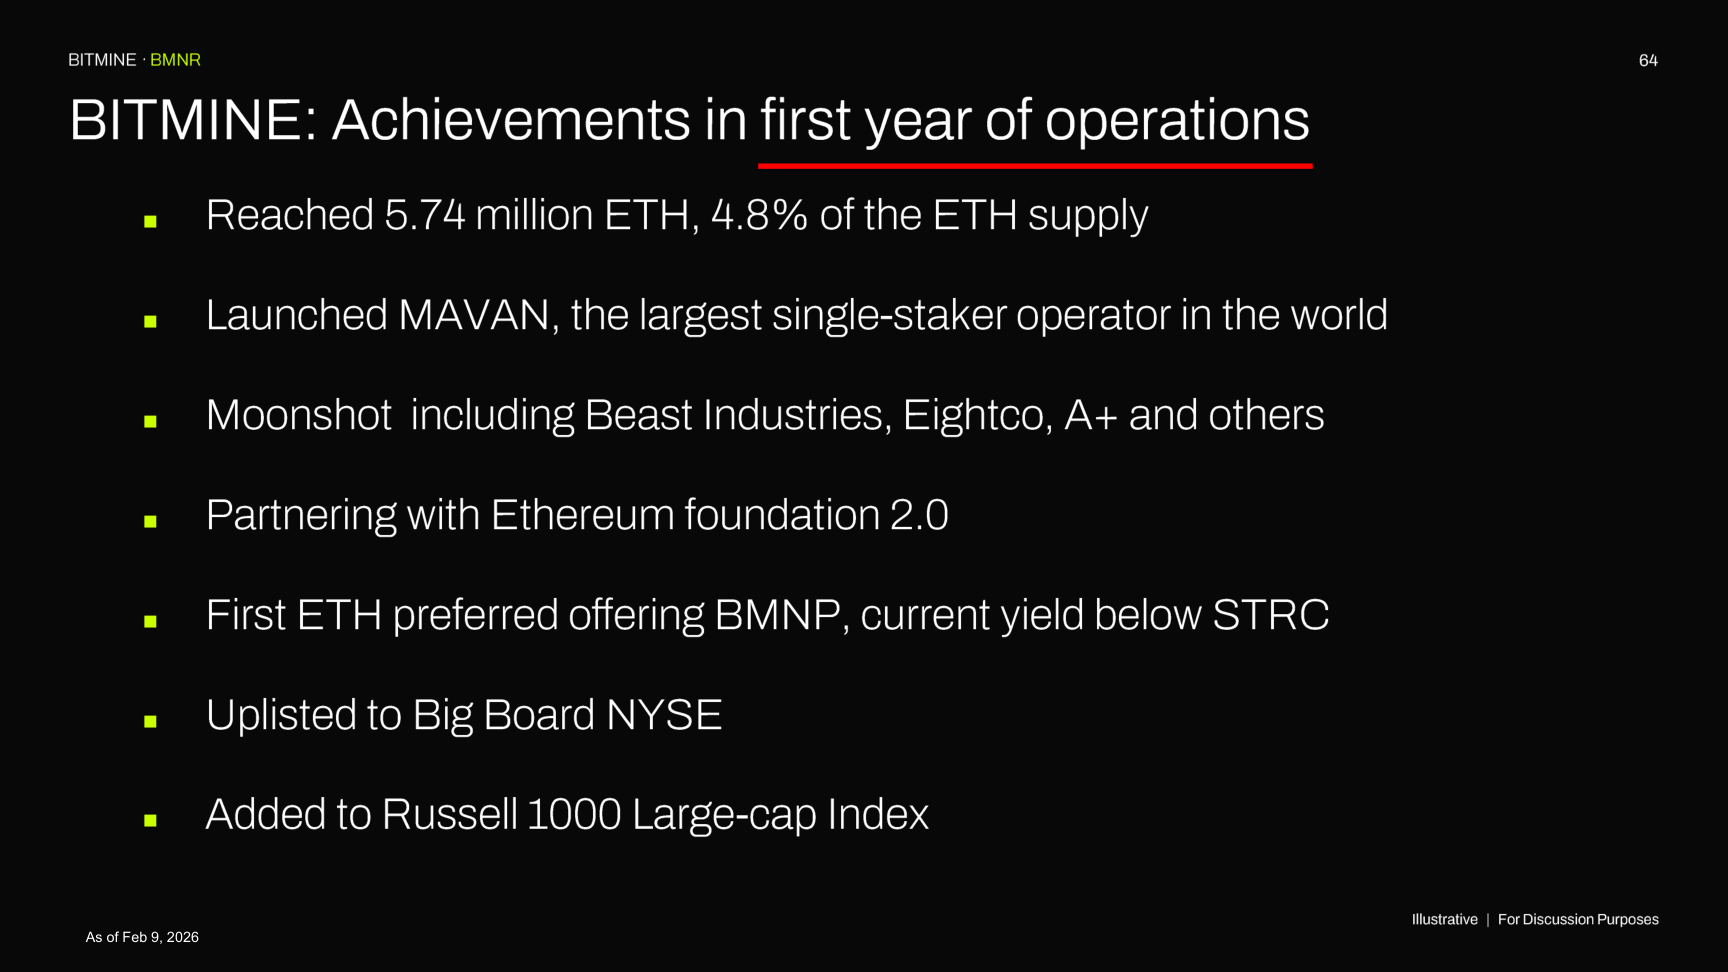
- Company disclosure (investor deck p64, July 2026): Seven bullets under "Achievements in first year of operations": 5.74 million ETH, or 4.8% of supply; MAVAN, "the largest single-staker operator in the world"; moonshot investments including Beast Industries, Eightco and A+; partnering with Ethereum Foundation 2.0 spin-offs; the first ETH preferred, BMNP; the NYSE uplisting; and the Russell 1000 addition.
- The bullets without numbers look like this in filings. MAVAN Holdings is 98% owned by the company and 2% by Ethereum Tower LLC. Eightco started as a $20 million purchase at $1.46 a share in September 2025 (7% of the company) and grew in March 2026 through a $75 million at-the-market purchase and $80 million of open-market buying at $0.92 a share to 100,655,143 shares, or 31.94%, with Tom Lee joining Eightco's board on March 10. BMNP is 3.5 million shares of 9.50% Series A perpetual preferred sold at $80 on June 4, 2026 for $273.8 million net.
Staking Revenue and Operating Costs
- The segment table in the quarterly income statement shows what the company sells. Figures are GAAP quarterly revenue.
| Segment | FQ3 2026 (May 31, 2026) | FQ2 2026 | FQ1 2026 |
| Staking and validation | $45.74 million | $10.20 million | $0.98 million |
| Self-mining | $0.62 million | $0.22 million | $0 |
| Consulting | $0.17 million | $0.20 million | $0.20 million |
| Leasing | $0 | $0.42 million | $1.11 million |
| Total | $46.54 million | $11.04 million | $2.29 million |
- Staking means depositing ETH with validator nodes and collecting network rewards. A line that did not exist three quarters earlier is now 98.3% of revenue. Gross margin was 87.8% and operating income turned positive for the first time at $3.92 million, which a business that uses almost no equipment or electricity will do. The company reports a 7-day yield of 2.61% and annualized staking revenue of about $330 million.
- The yield is not the company's to set. Rewards per validator thin out as more ETH is staked network-wide, so what the company decides is the staking ratio, 85.5%. Whether the other 14.5% is in transit, held for trading or pledged, the 10-Q does not say.
- Costs are set by contracts more than by payroll. There are three employees, and the staking infrastructure is run by the Australian team that came with Pier Two, inside a subsidiary. With Ethereum Tower the company had a consulting agreement (July 8, 2025) and a ten-year staking management agreement with a revenue-participation fee (March 24, 2026); the management agreement was mutually terminated on September 3. Accrued "digital asset management fees" were $6.71 million at May 31, double the $3.42 million at August 31, and the company guided twelve-month asset management fees at $40 to $50 million. The preferred dividend costs $26.6 million a year.
Is BMNR Stock Cheaper Than the Assets It Holds?
Market Cap Against Reported Assets
- Three multiples fail here. There is no P/E because the company loses money, P/S at 246.7x carries no information with $61.2 million of revenue, and fifteen months of listing history is not enough to draw a P/B band. Five fiscal year-ends look like this.
| Fiscal year-end | Year-end price | P/E | P/B | Dividend yield | FCF |
| Aug 2021 | OTC | Loss | n/a | None | -$0.05 million |
| Aug 2022 | OTC | Loss | n/a | None | -$4.40 million |
| Aug 2023 | OTC | Loss | n/a | None | -$1.42 million |
| Aug 2024 | OTC | Loss | n/a | None | -$0.11 million |
| Aug 2025 | $43.61 | 3.3x | 1.17x | None ($0.01 declared in FY2026) | -$5.18 million |
- The FY2025 P/E of 3.3x comes from the $13.39 EPS discussed below. The P/B of 1.17x divides $43.61 by book value per share of $37.40, which is $8.69 billion of equity over 232.4 million shares at August 31. Free cash flow is operating cash flow minus capex, negative in all five years; ETH purchases sit in investing cash flow and are not in it.
- So the sector divides market capitalization by the assets held, a ratio the market calls mNAV. Because the value depends on the denominator, here are four versions with the denominator, its date and what it deducts.
| Method | Denominator | Denominator date | Debt and preferred | Value |
| Market cap ÷ company-reported assets (crypto, cash and venture stakes, $15.7 billion) | Total assets at market | 2026-09-07 | Before debt, before preferred | 0.962 |
| Market cap ÷ (reported assets less preferred liquidation value of $280 million) | Total assets at market | 2026-09-07 | Preferred only | 0.979 |
| Market cap ÷ book equity in the 10-Q ($11.60 billion) | Book net assets (crypto at fair value) | 2026-05-31 | After debt, before the preferred issue | 1.302 |
| Aggregator P/B | Book net assets | 2026-05-31 | After debt | 1.25 |
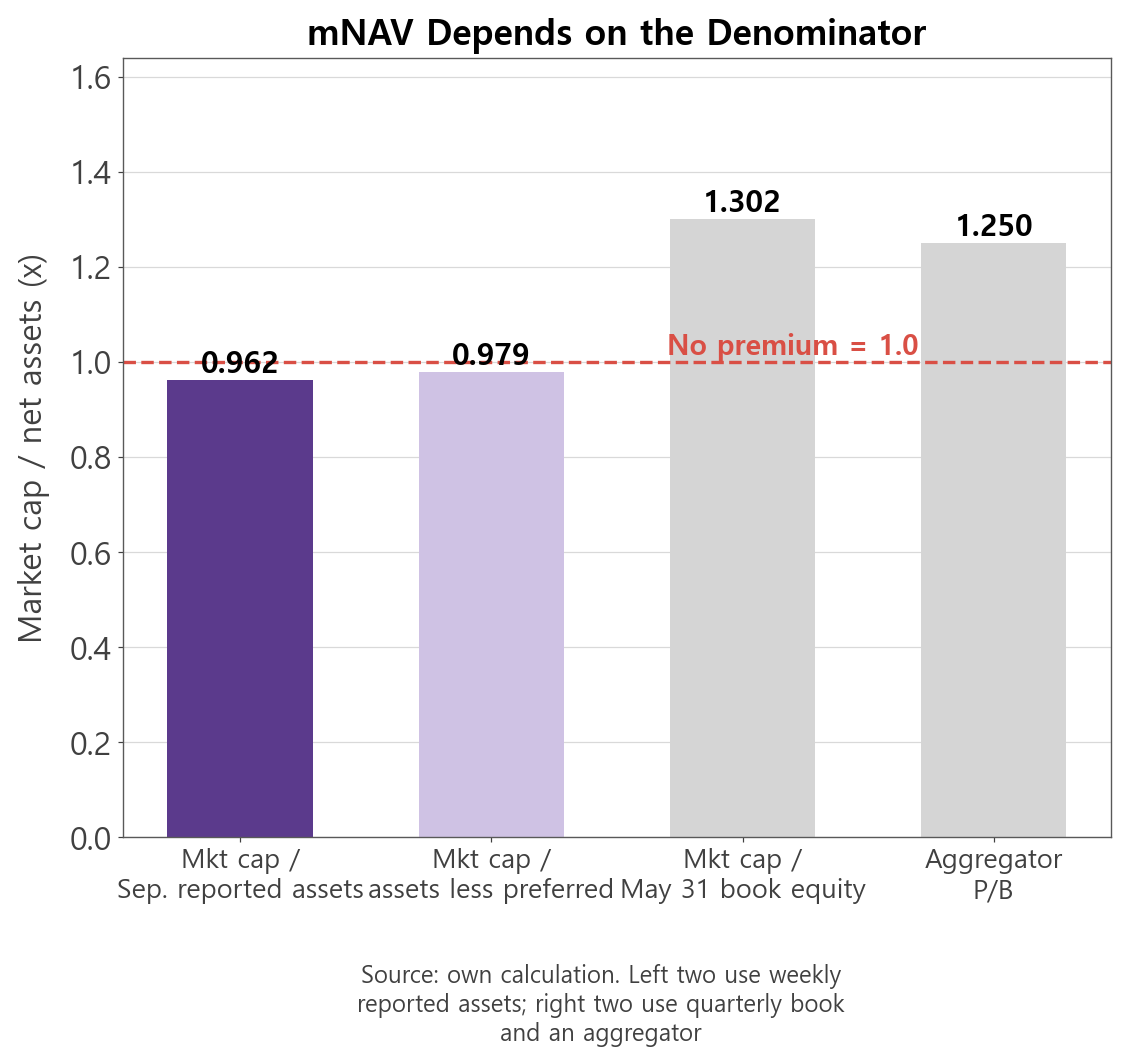
- The four numbers are not the same metric. The top two use the market-value assets the company tallies every week; the bottom two use book net assets at May 31. Because the company carries crypto at fair value, book equity equals net assets at May 31 prices, and it leaves out the 81,587 ETH bought since, the $273.8 million of preferred proceeds and the venture stakes. Total liabilities at May 31 were $30.13 million, 0.2% of assets, so deducting debt from the first row still gives 0.963. Since the company publishes its assets weekly, this article uses the first row, 0.962.
- Own calculation (same method as the August 26 close): The same calculation on August 26 gave 1.008. In three weeks market capitalization moved from $15.03 billion to $15.10 billion, +0.5%, while the company's reported assets went from $14.9 billion to $15.7 billion, +5.4%.
- ETH rose only 2% in those three weeks. The company bought more ETH and its cash and venture stakes grew, so the ratio slipped under 1 because of the denominator more than the price.
- The numerator carries an assumption too. The share count is the 603.2 million on the July 9 cover page, and whether ATM sales have added to it will not be known until the next annual report. If they have, market capitalization is higher than shown here and the ratio is closer to 1.
Price vs ETH Price: The 0.015 Formula
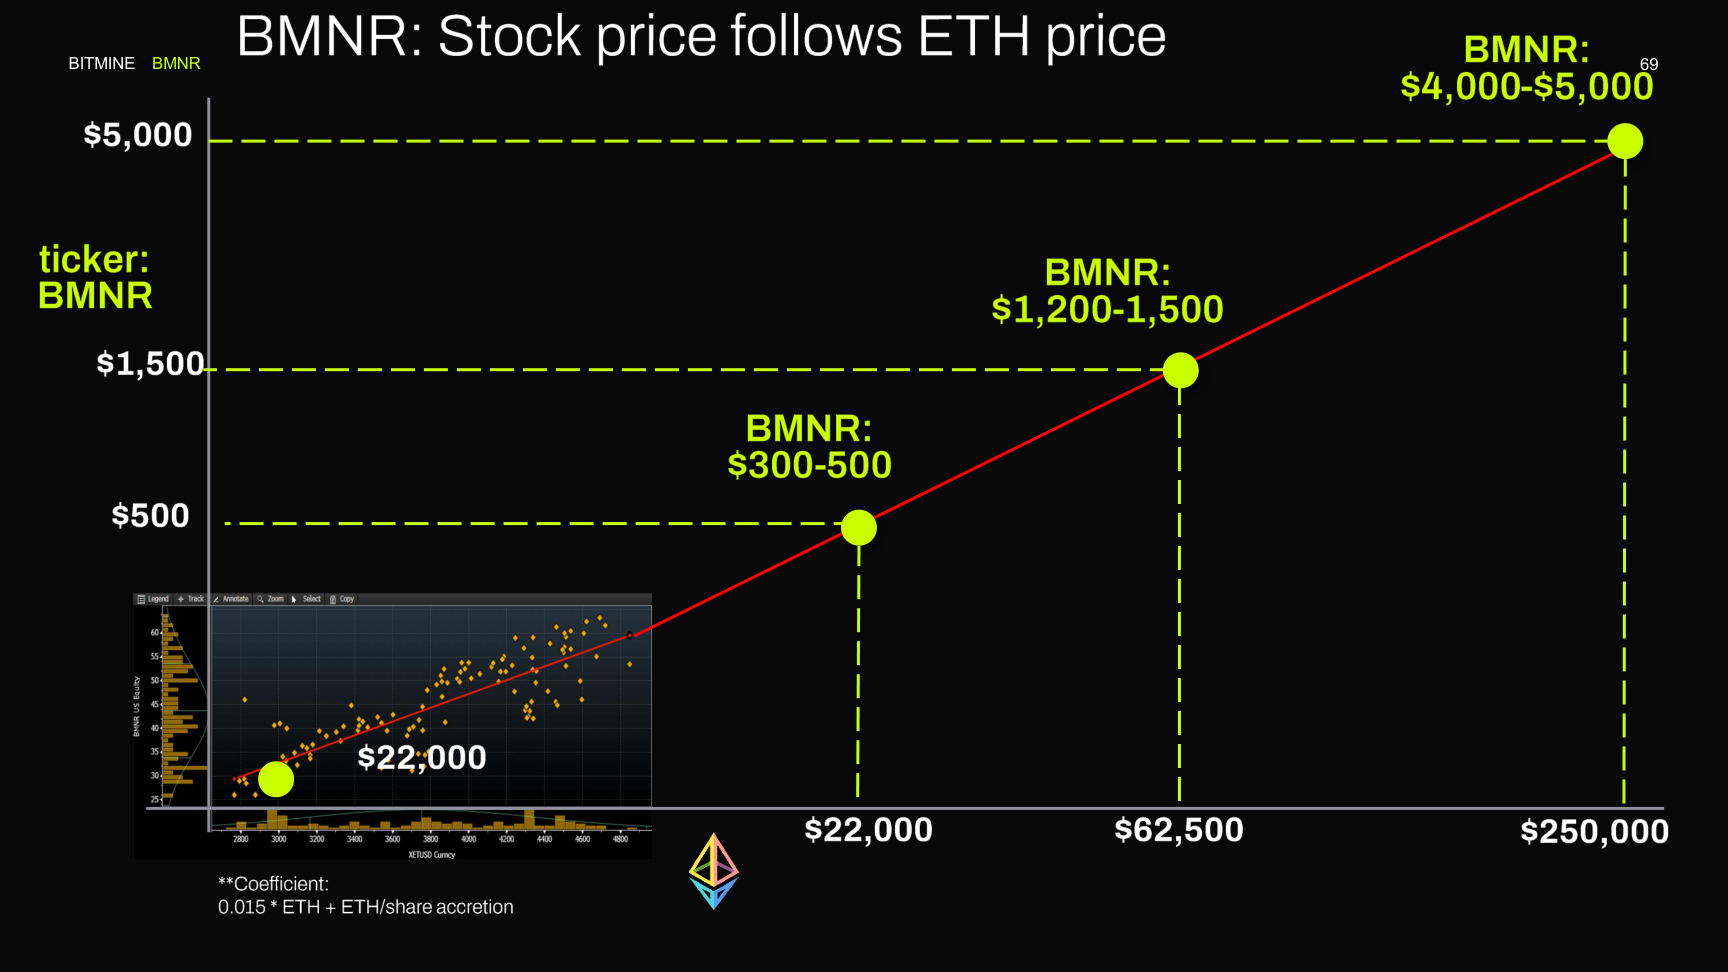
- Company disclosure (investor deck p68 and p69): Slide 68 is titled "BMNR: Stock price follows ETH price." Slide 69 gives the coefficient: share price = 0.015 × ETH price + ETH-per-share accretion. The table on the same slide maps $22,000 ETH to a $300 to $500 share price, $62,500 to $1,200 to $1,500, and $250,000 to $4,000 to $5,000. In the video the chairman puts the correlation between the two at 90%.
- Own calculation (share price ÷ ETH price): Multiply 0.015 by the $2,495 ETH price the company printed in its weekly release and you get $37.43. The stock is at $25.03. The coefficient the market is actually using is 25.03 ÷ 2,495 = 0.010.
- The coefficient is three things multiplied together. Each share carries 0.00983 ETH (5,929,198 divided by 603.2 million shares, on the July 9 count). That much ETH is worth $24.53 at $2,495. The $25.03 share price divided by $24.53 is 1.02, and that 1.02 is what the market pays per dollar of ETH inside the share. Run the company's 0.015 through the same division and you get 0.015 ÷ 0.00983 = 1.53. The coefficient the company wrote into its formula assumed the market would pay 1.53 times the ETH value inside each share; the market currently pays 1.02.
- On an ETH-only basis the ratio is 1.02; on the all-assets basis of the previous section it is 0.96. The gap is the $600 to $700 million of cash and venture stakes that sit in the denominator of one and not the other.
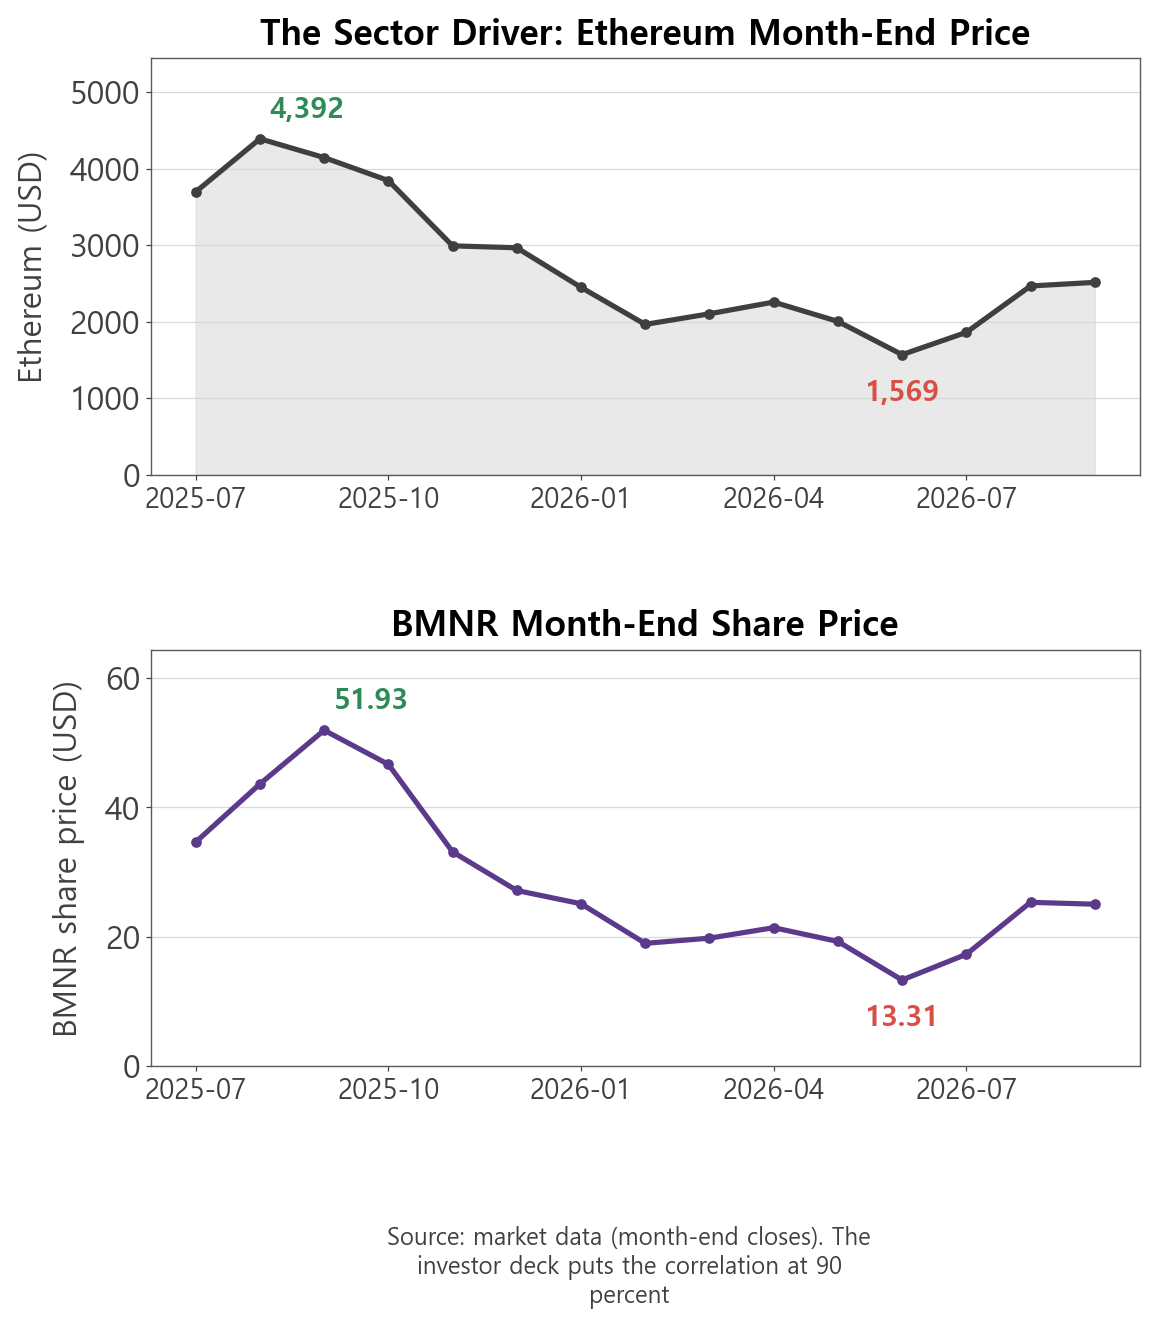
- The 90% correlation holds in month-end closes. From the August 2025 high of $4,392 to the June 2026 low of $1,630 ETH fell 63%; the stock went from $43.62 to $13.31, down 69%. But correlation and coefficient are different claims. The market sets the first term; the only term the company controls is ETH-per-share accretion.
How Share Issuance Affects Existing Holders
- Five numbers in the financial statements set the direction for everything else.
| Number | Value | Effect on the investment case |
| Market cap ÷ reported assets | 0.962 | Below 1, selling new shares to buy assets lowers assets per share |
| ETH per share (May 31) | 0.009345 | The company's own scorecard metric; it fell once, in the February quarter |
| Average ATM sale price (nine months) | $34.84 | 39% above the current $25.03; the ratio was above 1 then |
| Nine-month ETH mark-to-market loss | $9.04 billion | 99.3% of the $9.11 billion net loss; no cash left the company |
| Quarterly staking revenue | $45.74 million | 98.3% of revenue and the source of the first operating profit, $3.92 million |
ETH per Share Over Time
- Here is the first row worked through with numbers. Reported assets of $15.7 billion over 603.2 million shares is $26.03 of assets per share against a $25.03 share price. Sell one new share at that price and buy ETH with the proceeds (ignoring fees): assets rise by $25.03, the share count rises by one, and assets per share fall below $26.03. The new shareholder pays $25.03 and receives $26.03 of assets, so the new holder is not the one who loses; existing holders' assets per share are. When the company sold 340,748,312 shares over nine months at an average of $34.84, above assets per share at the time, existing holders' assets per share rose. Whether issuance helps or hurts holders comes down to the sale price against assets per share, with fees and any proceeds not spent on ETH as conditions.
- Own calculation (holdings ÷ 10-Q share counts): ETH per share was 0.008067 at August 31, 2025, 0.009192 at November 30, 0.009058 at February 28, 2026 and 0.009345 at May 31.
- In the February quarter the company bought 747,088 more ETH and still lost ground, 1.46%, because it issued 88.51 million new shares while ETH had fallen from the $3,000s to $1,958. The company's January 12, 2026 press release said "we have only issued shares at a premium to mNAV," and for that quarter the sentence did not hold. After May 31 there is no quarterly share count, so 0.00983 on the July cover count is a ceiling on the assumption that no shares were repurchased since. A $1 billion buyback was authorized on July 25, 2025 (8-K) and the May 31 10-Q shows no repurchases.
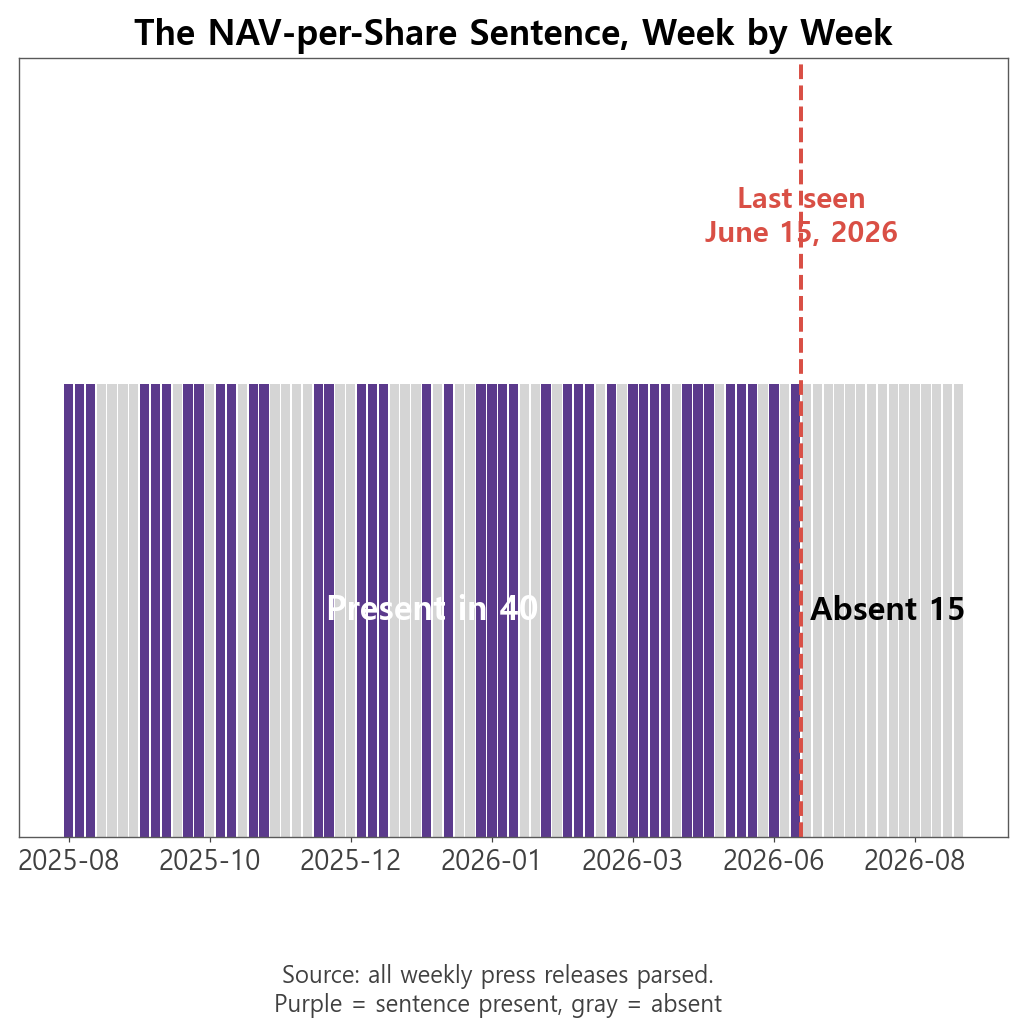
- The change in the company's own language dates the shift. The sentence "we lead our peers in the velocity of raising crypto NAV per share" appeared in 40 weekly releases from August 4, 2025 through June 15, 2026, and has been absent from 15 consecutive releases since June 18, the week Ethereum printed its cycle low of $1,630.
- The capital picture is three lines: $20.37 billion of paid-in capital, an accumulated deficit of $8.77 billion, and equity of $11.60 billion. Most of the deficit is the gap between an average ETH cost of $3,517.14 and a May 31 carrying price of $2,004 passing through the income statement. Cash rose from $340.29 million at May 31 to $593 million in the September 7 release. The 9.50% preferred costs $26.6 million a year in dividends, which the $330 million annualized staking revenue covers, and the ATM program has $24.5 billion of remaining capacity, 1.6 times the market capitalization. The source is the fiscal Q3 2026 Form 10-Q.
What Tom Lee and the Street Expect
The July 2026 Deck and the ETH 2.0 Thesis
- The newest presentation on Bitmine's investor page is a 72-slide deck from July 2026 whose title borrows a robotics term for the unease people feel toward near-human machines and applies it to wealth created by AI. It shares its title with the July 2026 Chairman's Message and is essentially Tom Lee's video script turned into slides, in three parts: macro headwinds in early 2026 with signs of a bottom, why the future market for Ethereum is exponential, and why Bitmine is primed for the next bull cycle.
- Company disclosure (investor deck p6 and p7, July 2026): Five reasons crypto was weak in the first half of 2026: Fed expectations flipped from four cuts to 1.6 hikes, the Clarity Act sits at a 44% probability of passage on prediction markets, 86% of venture dollars went to AI, financials underperformed, and "crypto spring is not a straight line higher."
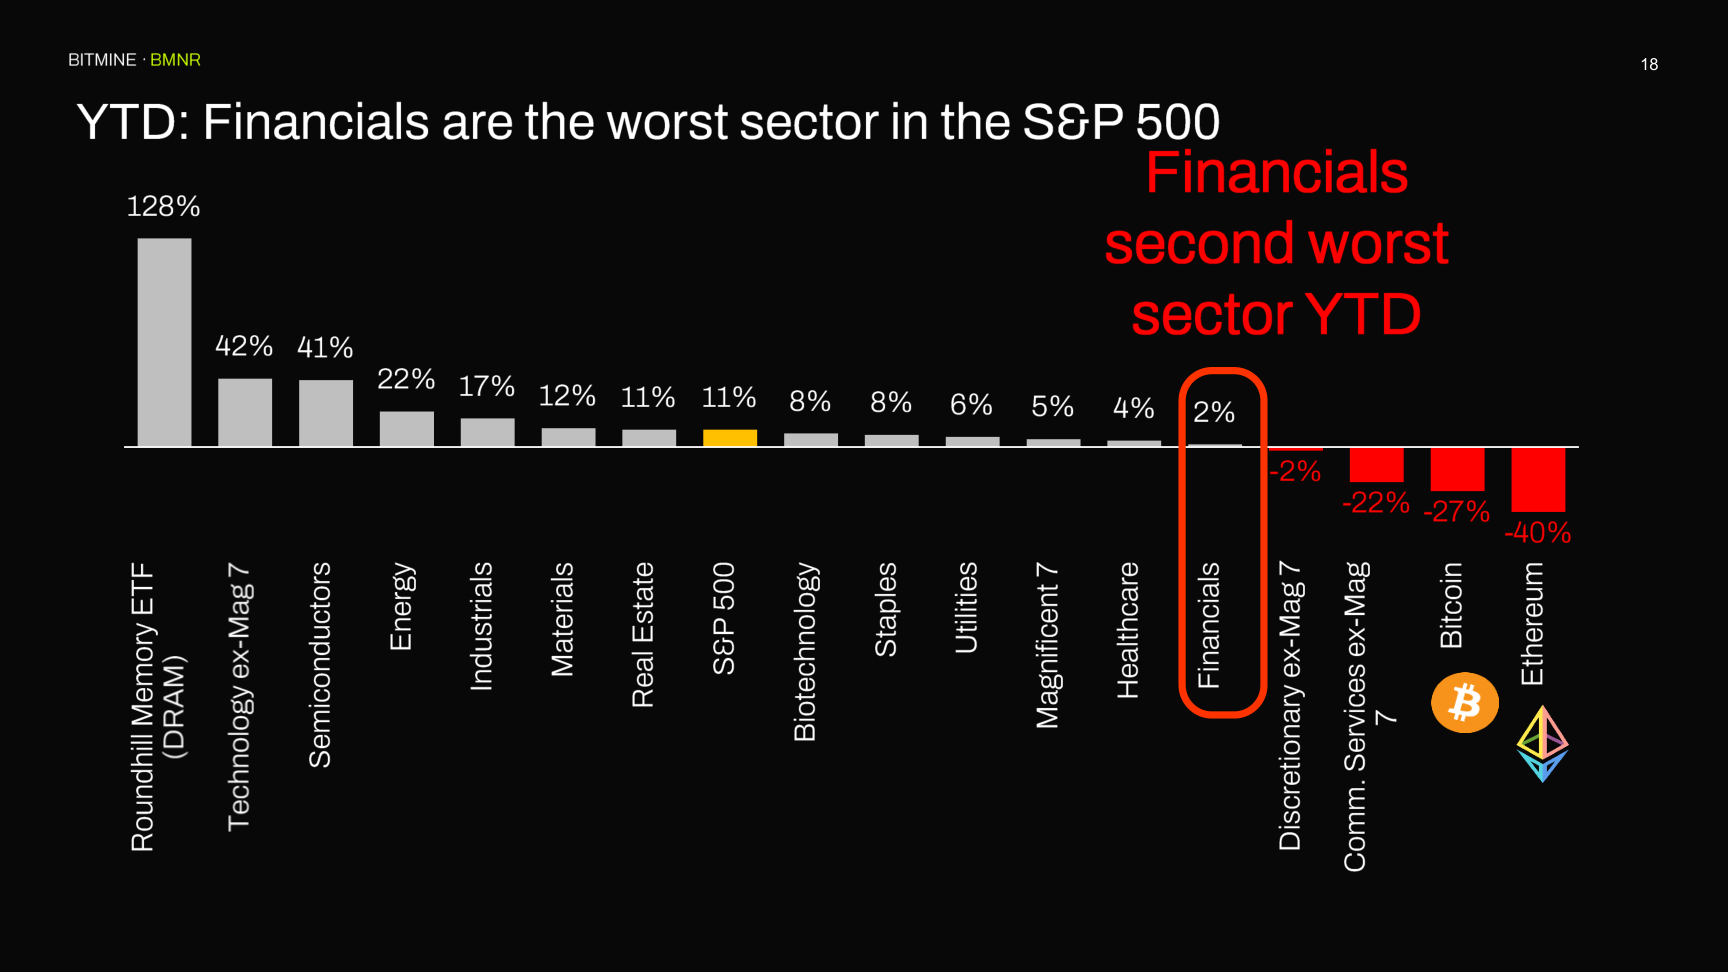
- Slide 18 sizes the headwind. In the deck's year-to-date table Ethereum sits at the bottom at -40% with Bitcoin at -27%, while semiconductors are up 41% and the S&P 500 is up 11%. Slides 20 through 22 make the bottom call: DeMark Analytics, the company's timing advisor for market purchases, used a 1987 S&P 500 analog to point at roughly $2,225 in August, and Stephen Suttmeier, formerly of Bank of America, set moving-average conditions at $1,708 to $1,693 and $1,846 to $1,876.
- Own calculation (ETH month-end closes): Ethereum closed August at $2,467, above the deck's August level. The argument belongs to two outside technicians, and the deck does not connect their levels to Bitmine's own buying schedule.
- Part two is "ETH 2.0." Slides 25 to 44 define Ethereum 1.0 as the ICO boom, the NFT boom, ETFs and stablecoins, note the two peaks at $4,866 and $4,955 and the drawdown to $1,875, and line up Amazon ($6 to $241), Nvidia ($1 to $197) and JPMorgan ($58 to $334) as examples of what happens to a price when the addressable market widens.
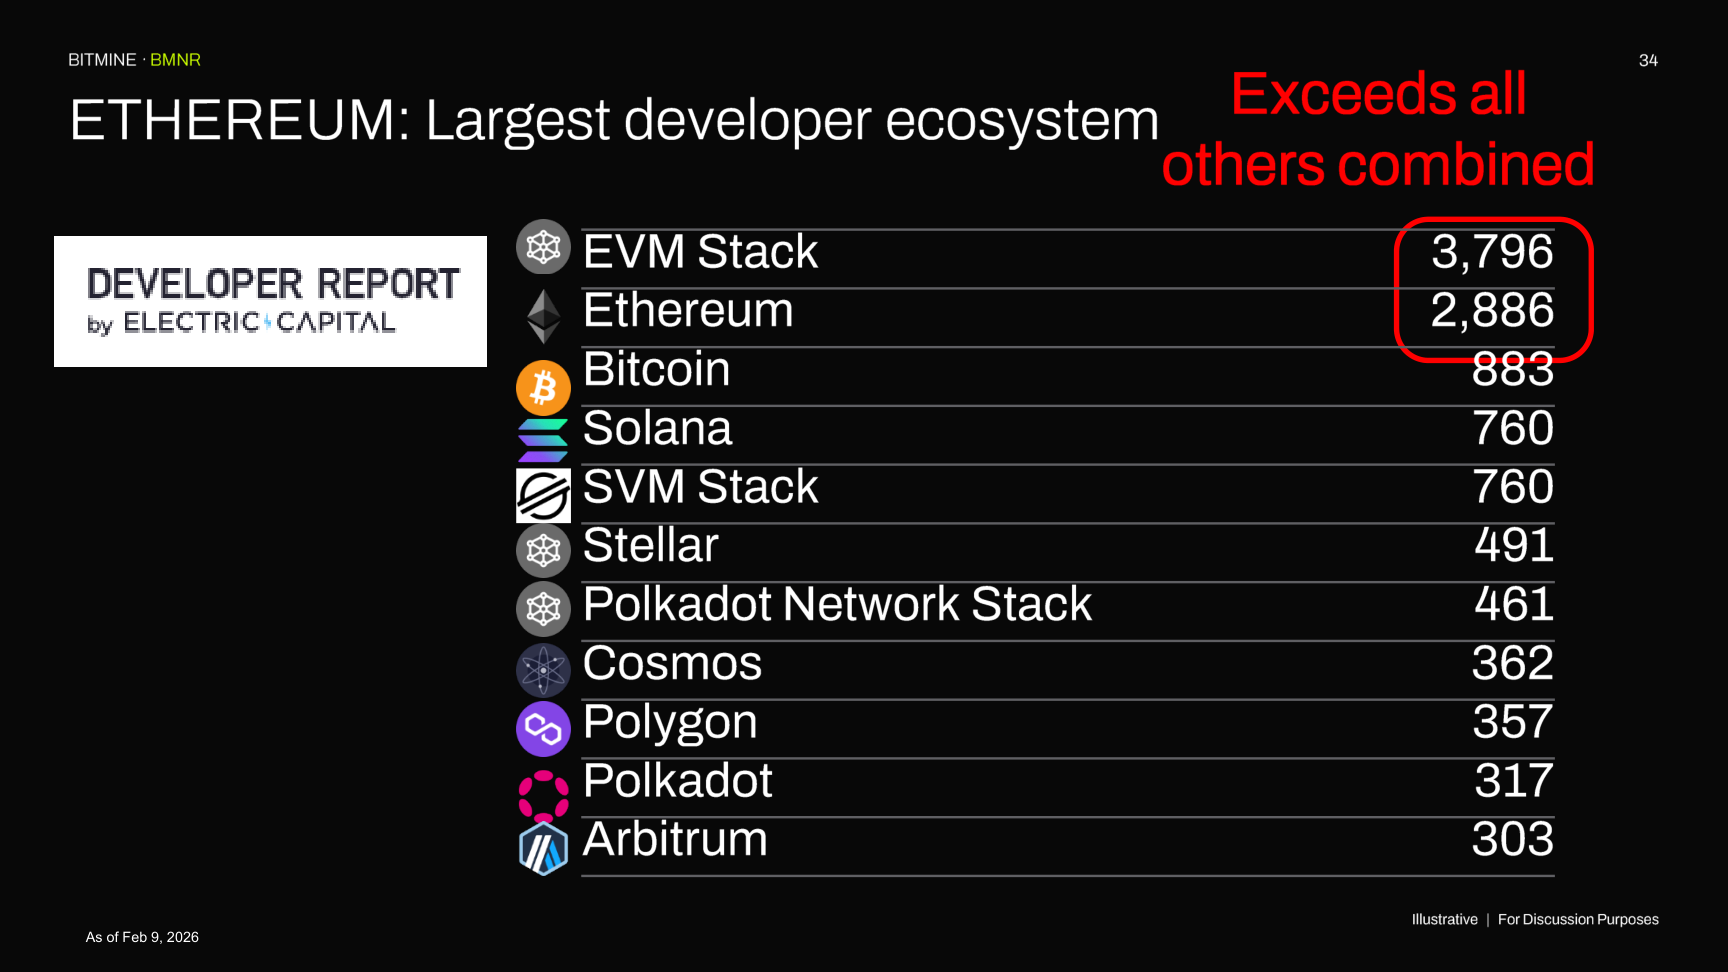
- Company disclosure (investor deck p28 and p34): The evidence that "Wall Street favors Ethereum" is a list: BlackRock's BUIDL, JPMorgan's MONY, Securitize, Ondo Finance, Robinhood Chain on Arbitrum, Coinbase's Base and Kraken's Ink. Slide 34 counts developers: 3,796 on the EVM stack, 2,886 on Ethereum, 883 on Bitcoin and 760 on Solana, which the deck says "exceeds all others combined."
- These two slides carry the densest outside numbers in the deck, sourced to Fundstrat and CoinMarketCap. The chairman's claim that Robinhood Chain processed $560 million on July 9 and has since crossed $1 billion is Robinhood's figure, not something a Bitmine filing can confirm; it goes into the verdict table as unverified.
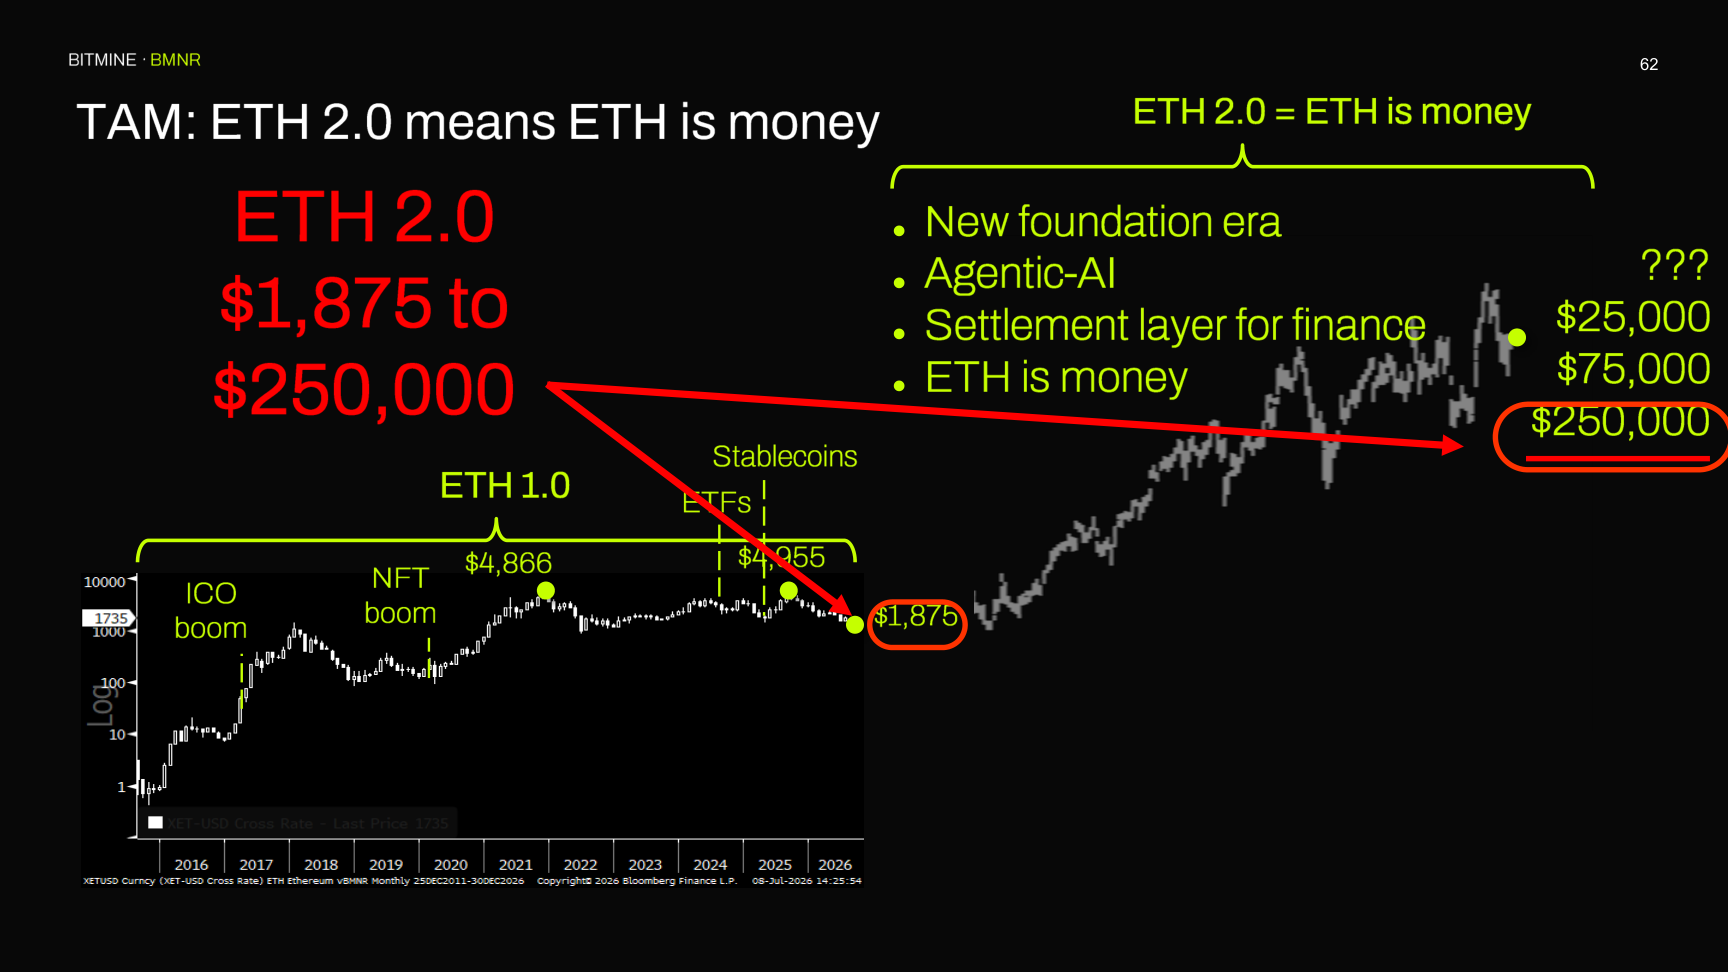
- Company disclosure (investor deck p62): The ETH 2.0 price scenarios are $25,000, $75,000 and $250,000. The $250,000 figure is attributed to Ethereum co-founder Joe Lubin's "100x" comment and to a report by Etherealize. In the video the chairman says, "Where do I land? I don't know," and then, "1,800 to 250,000 is roughly 100x."
- Slides 45 to 61 are the title concept, borrowing Masahiro Mori's 1970 robotics hypothesis to argue that when AI creates more wealth than its users, humans will fear it, that the trust layer between humans and AI will be a smart-contract blockchain, and that this is why ETH becomes money. Of 72 slides, the ones with Bitmine's own financial or operating figures are 64, 66, 67, 68, 69 and 71, eight with the cover and contents. The other 64 are about Ethereum, macro and AI. That split shows what the company wants to explain to investors; it is not a measure of the deck's worth. The one test this article applies is where the deck explains the difference between buying ETH and buying this stock, and that lives on one slide, the formula on page 69, covered above. Most source lines read "Source: Fundstrat," the research firm the chairman co-founded and runs.
- The second deck on the same page is a 27-slide results presentation. Its cover is dated July 17, 2025, but the content covers fiscal 2025 and a dividend declared November 21, 2025, so it reads as a November 2025 update.
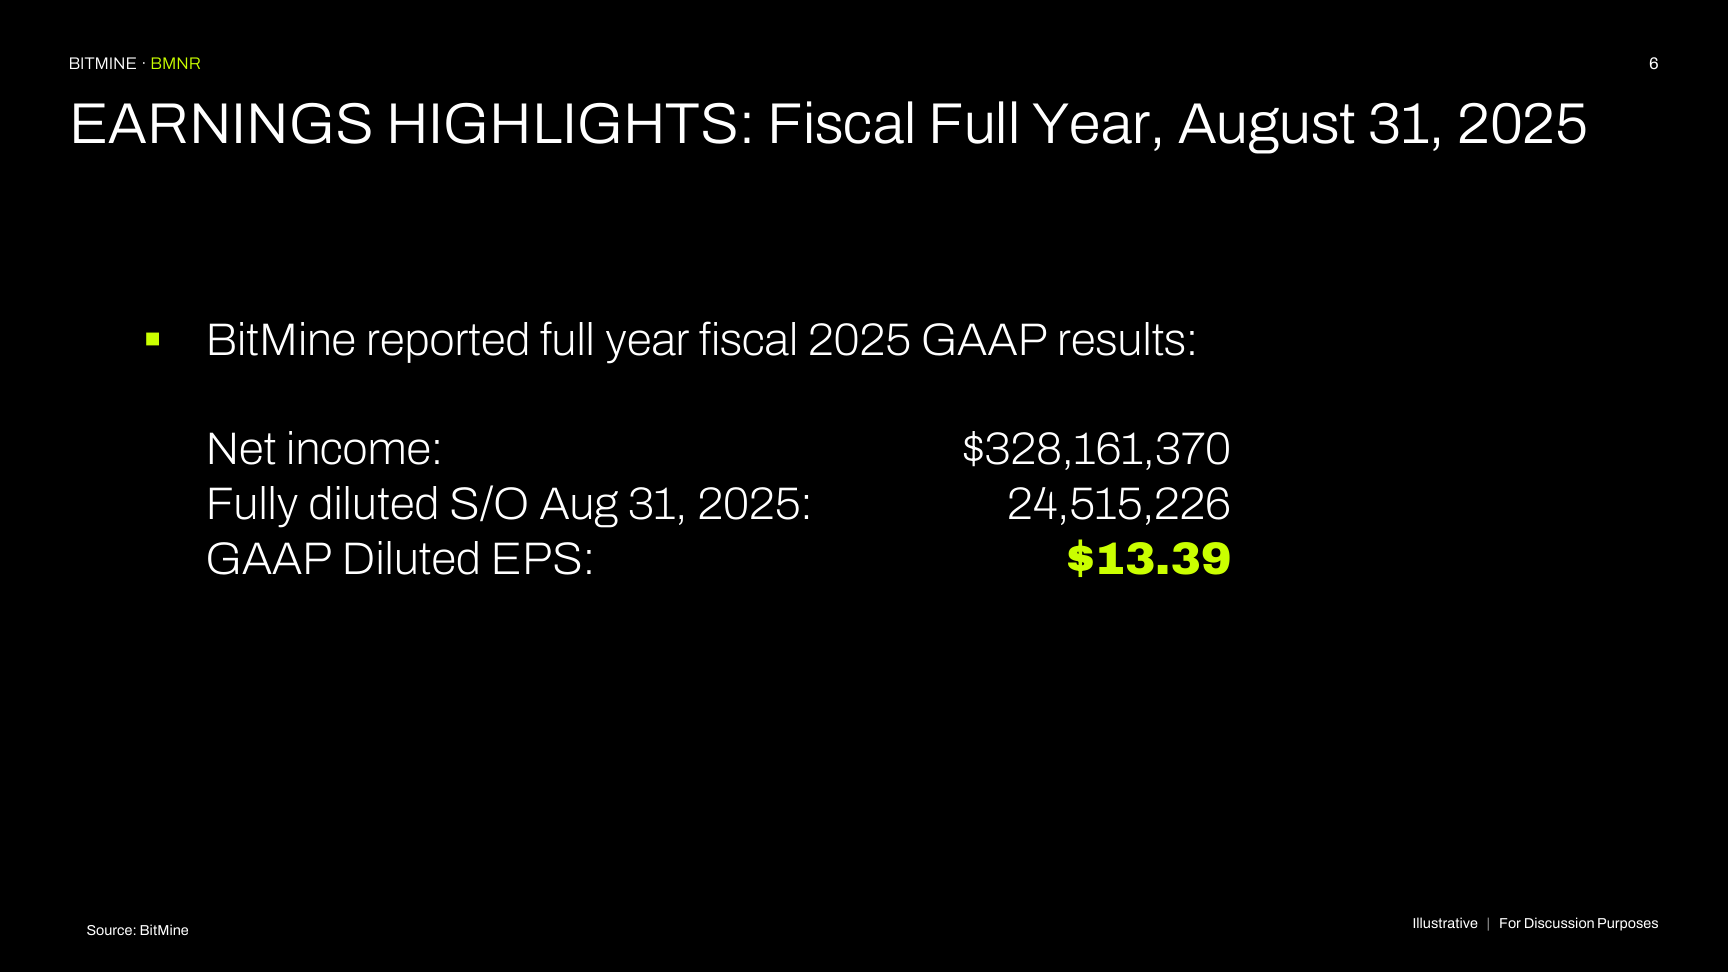
- Company disclosure (results deck p6, November 2025): FY2025 GAAP net income of $328,161,370, fully diluted shares outstanding at August 31, 2025 of 24,515,226, and GAAP diluted EPS of $13.39.
- Filing footnote (10-K XBRL): The net income tag for the same fiscal year reads $348,577,000, $20.4 million above the deck. It looks like a before-and-after-preferred distinction, but the company does not say which basis the deck uses, so the table records it as unverified.
- The reason $13.39 will not repeat is the denominator. The 24.5 million weighted-average count is an average dragged down by the placement and ATM sales all landing in July and August; actual shares at August 31 were 232.4 million. The numerator is two months of ETH mark-to-market gains: operating income was $444.2 million on revenue of $6.1 million. Nine months into FY2026 the net loss is $9.11 billion, and the two covering analysts have FY2026 EPS at -$21.885.
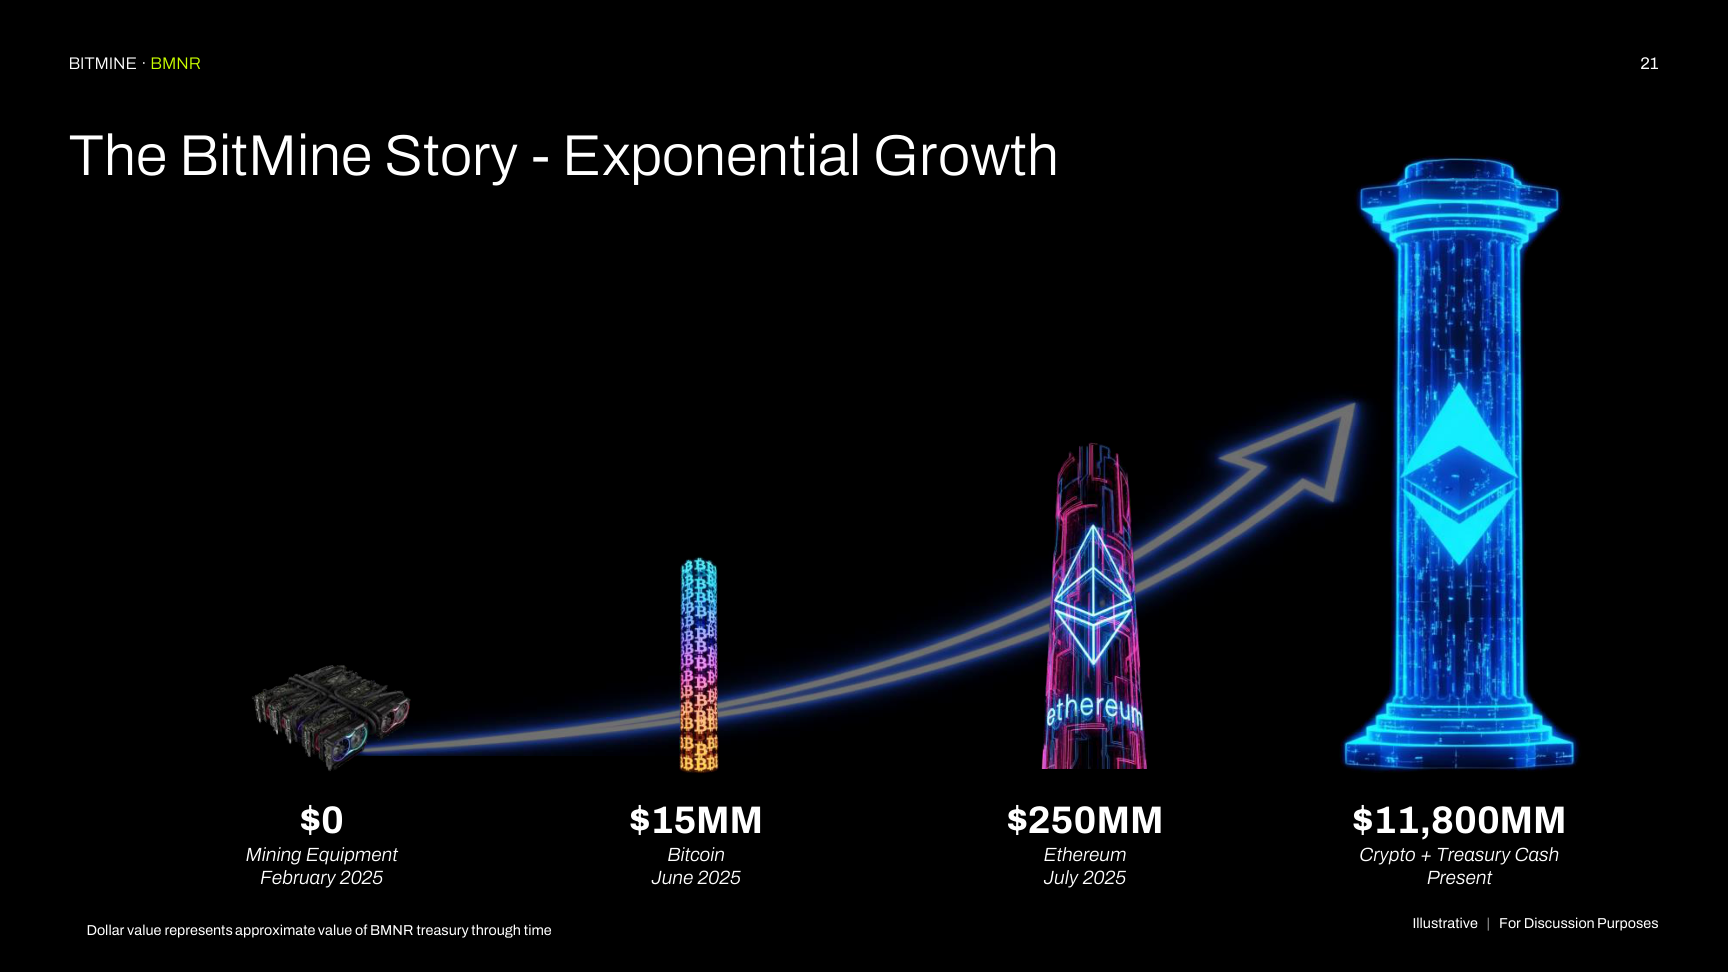
- Company disclosure (results deck p21): "The BitMine Story, Exponential Growth." February 2025, $0 in mining equipment. June 2025, $15 million of Bitcoin. July 2025, $250 million of Ethereum. Then $11.8 billion. The latest weekly release puts the same figure at $15.7 billion.
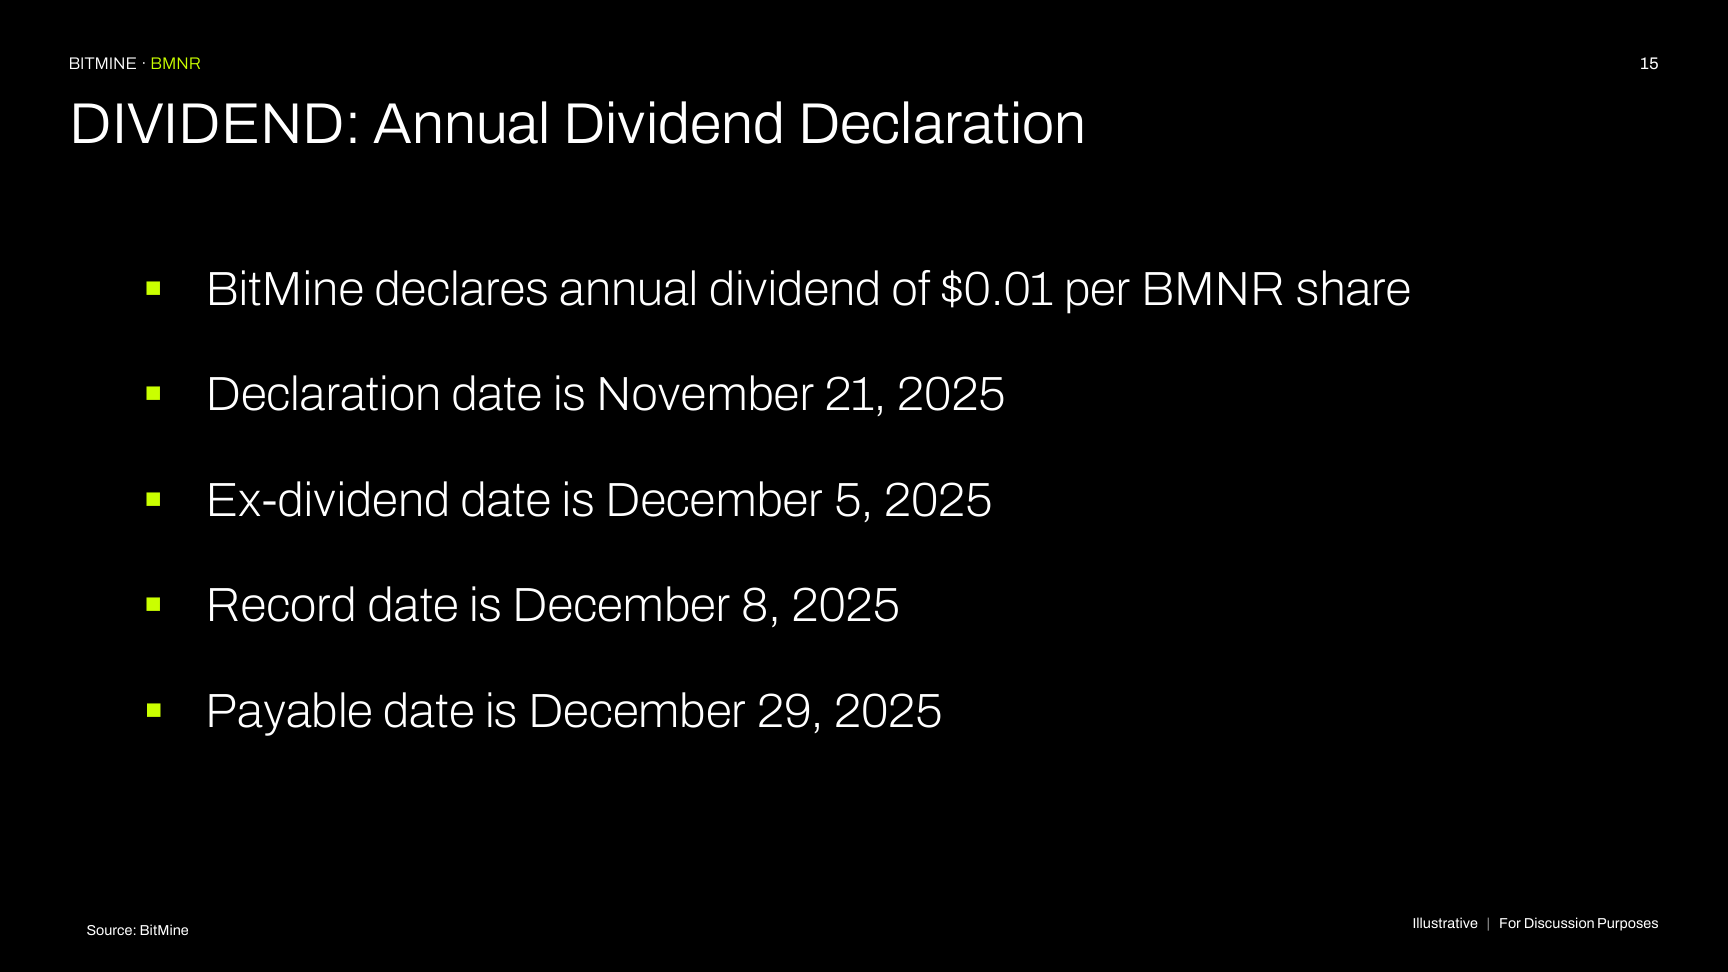
- Company disclosure (results deck p15 and p17): An annual common dividend of $0.01 per share, declared November 21, 2025, payable December 29. Slide 17 is titled "BMNR only large-cap crypto stock to pay dividend." One cent on a $25.03 share is a 0.04% yield, and the cash flow statement shows $4.26 million of dividends paid over nine months.
- One more change matters for every fiscal-year comparison the decks make. On July 9, 2026 the board moved the fiscal year-end from August 31 to December 31. After the FY2026 10-K there will be a four-month transition report on Form 10-KT covering September through December 2026.
12 Bull Arguments Checked Against Filings
- I collected the arguments for owning BMNR from the investor deck, the Chairman's Message, analyst notes and investor communities, and tested each against filings.
| # | The thesis | Evidence | Verdict |
| 1 | Ethereum bottomed at $1,630 in June | Deck p20-22 outside technical work; August close $2,467 | Partly holds |
| 2 | ETH 2.0 takes the price to $25,000-$250,000 | Deck p62; Lubin and Etherealize cited | Unverified |
| 3 | Share price = 0.015 × ETH with 90% correlation | Deck p69; own calculation gives 0.010 | Overstated |
| 4 | Largest holder at 4.9% of supply earns a scarcity premium | Weekly 8-K; market cap to assets 0.962 | Conditional |
| 5 | Staking yields $330 million a year and three employees mean operating profit | 10-Q FQ3 staking revenue $45.74 million; operating income $3.92 million | Partly holds |
| 6 | Shares are only issued at a premium, so issuance grows ETH per share | 10-Q quarterly shares and holdings; February quarter -1.46% | Overstated |
| 7 | NYSE listing and Russell 1000 bring institutions | Vanguard 13G 5.13%; ARK 13F 9.70 million to 8.81 million shares | Partly holds |
| 8 | Moonshots (Eightco 31.94% and others) add upside | 10-Q Note 6; $175 million invested | Conditional |
| 9 | 9.50% preferred BMNP funds ETH without dilution | 8-K June 5, 2026; $273.8 million net | Holds |
| 10 | The Clarity Act re-rates crypto | Deck p11-13; 44% on prediction markets | Conditional |
| 11 | The bear market bottoms in October; target $63.60 | Cantor Fitzgerald note | Unverified |
| 12 | The company has never sold ETH | 100 weekly 8-Ks; net holdings never fell week over week | Partly holds |
- Outside view (Cantor Fitzgerald research, September 2026): The note frames Bitmine as "a leveraged proxy for Ethereum's price movements," expects the drawdown to find a floor around October 2026, and lists as risks the absence of an operating cash-flow cushion, the concentration in a single asset, and the fact that staking yields are themselves denominated in ETH.
- Outside view (investor community forecast post, June 2026): Titled "5% is the bait, the real trigger is ETH per share," the post set a six-month target return of 77.51%. The company's own scorecard metric is the one the market watches.
- Claim 4 separates a fact from a forecast. Being the largest holder is a fact; that a premium will attach to it is a forecast, and a ratio below 1 today does not refute it. The argument only works when the ratio is above 1, hence conditional. Claim 6 is a sentence from the company's January 12, 2026 press release, and it did not hold in the February quarter. Claim 12 is limited by what the weekly data can show: net holdings never fell from one week to the next, which does not rule out sales inside a week.
Price Targets and Analyst Revisions
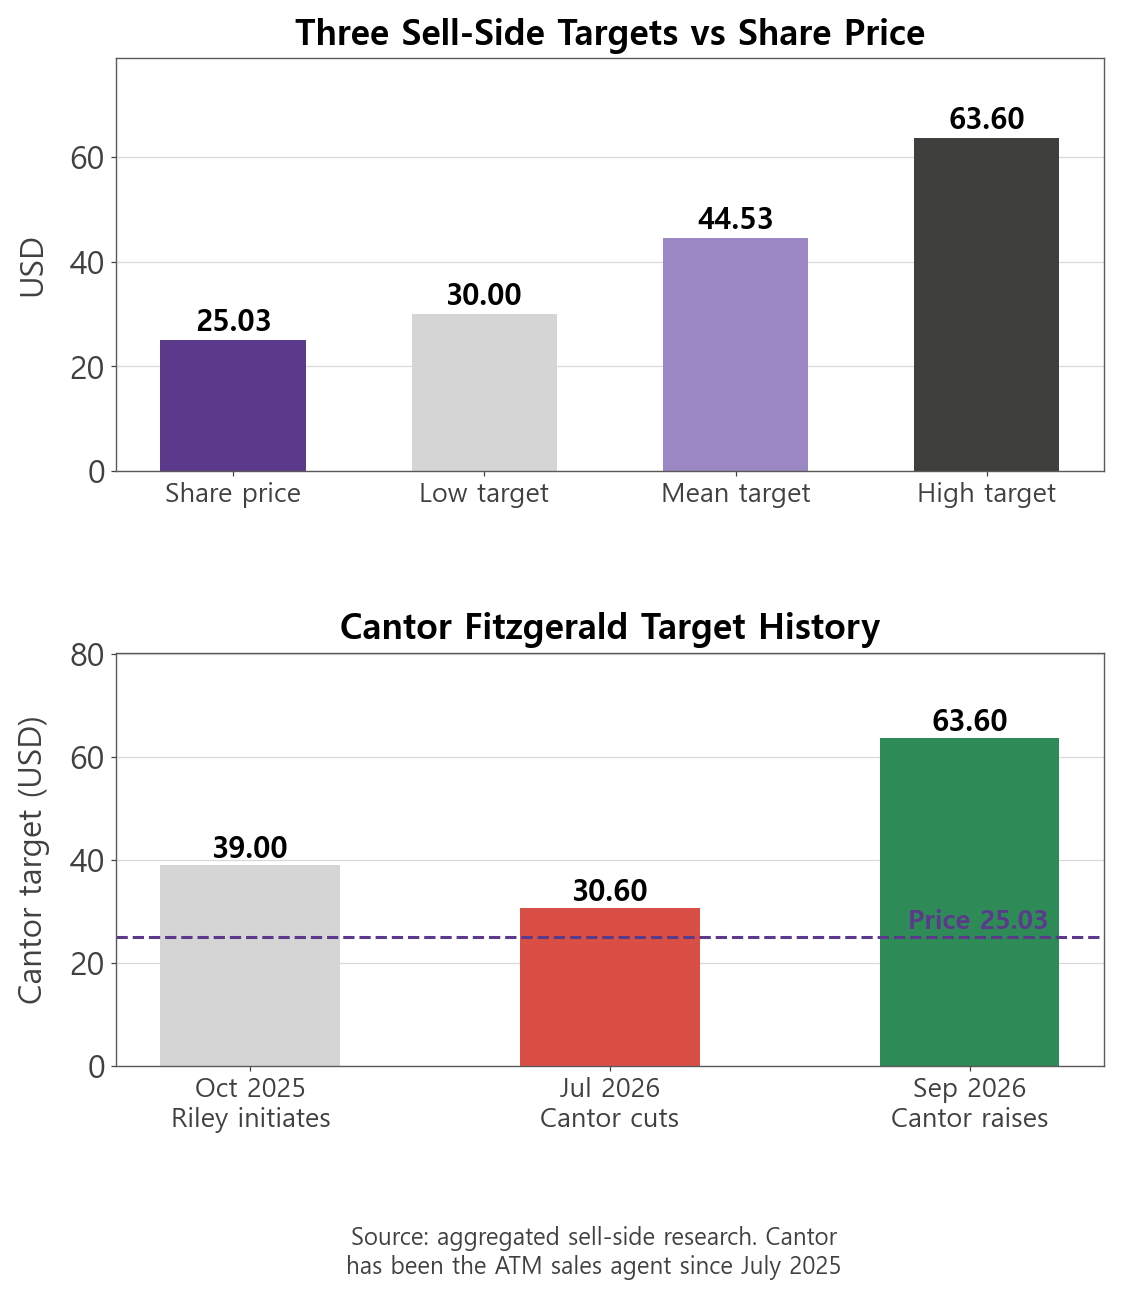
- Three brokers cover the stock. Aggregated sell-side research puts the mean target at $44.53, the low at $30 and the high at $63.60, and all three ratings are Buy-equivalent.
| Date | Firm | Rating | Target |
| 2026-09-10 | Cantor Fitzgerald | Overweight, maintained | $30.60 to $63.60 |
| 2026-09-04 | B. Riley | Buy, maintained | Not disclosed |
| 2026-07-01 | Cantor Fitzgerald | Overweight, maintained | $39 to $30.60 |
| 2026-02-24 | B. Riley | Buy, maintained | Not disclosed |
| 2025-10-16 | B. Riley | Buy, initiated | Not disclosed |
- Aggregator cross-check (aggregated sell-side estimates): The FY2026 (August year-end) EPS estimate is -$21.885 across two analysts, with one downward revision in the last 30 days and the 90-day-ago figure at -$15.82. FY2027 EPS is +$0.64 and FY2027 revenue $595 million. Because this company's EPS estimate is an ETH price estimate, a revision downward means an analyst lowered their ETH assumption.
- Bitmine does not hold a quarterly earnings call. It issues a press release on results day, and management commentary comes through the Chairman's Message videos. In the July message Tom Lee said, "So our future price for Bitmine stock is heavily dependent on the future price of Ethereum." Had there been an earnings call, that sentence would have been the guidance.
- Cantor's September 10 note doubled the target it had cut to $30.60 two months earlier, on the argument that the ETH bear market bottoms around October. One fact belongs next to that upgrade. Under the July 9, 2025 8-K, the sales agents for the company's $2 billion at-the-market program are Cantor Fitzgerald and ThinkEquity. Research and capital markets are supposed to sit behind a wall, and this article did not verify the conflict disclosures in the note itself. The point is to read the target alongside that relationship, not to claim the relationship makes the target wrong.
Major Shareholders and Management
- I read the beneficial-ownership filings and the 13F holdings tables of 20 well-known investors. Directors and officers together held 855,146 shares in the December 9, 2025 proxy, 0.14% of the company; chairman Tom Lee held 226,722 shares (DEF 14A).
| Holder | Common shares | Stake | Source |
| Vanguard Capital Management | 23,340,410 | 5.13% | 13G, Apr 29, 2026 |
| ARK Investment Management | 8,811,588 | 1.46% | 13F, Jun 30, 2026 |
| Citadel Advisors | 3,302,118 (call options on 6,391,600 and put options on 5,270,600 shares reported separately) | 0.55% | 13F, Jun 30, 2026 |
| D. E. Shaw | 2,070,201 | 0.34% | 13F, Jun 30, 2026 |
| Tudor Investment | 501,000 | 0.08% | 13F, Jun 30, 2026 |
| Millennium Management | 249,600 | 0.04% | 13F, Jun 30, 2026 |
| Directors and officers (10) | 855,146 | 0.14% | Proxy, Dec 9, 2025 |
- Stakes are recomputed on the July 9 cover count of 603.2 million shares, so they differ slightly from the 5.13% printed in Vanguard's 13G. Citadel's call and put positions are reported in share-equivalent terms in the 13F table but are not common stock, so they are excluded from the stake.
- Some early investors reduced their holdings. Peter Thiel's Founders Fund (FF Consumer Growth II) reported 3,926,759 shares, or 7.0%, in a 13G on July 15, 2025, and 1,963,380 shares, or 0.7%, in an amendment on November 14. Half the shares were sold; the rest of the drop in percentage terms is dilution, as the share count grew from 56 million to more than 400 million over the same period. ARK cut from 9,699,165 shares at March 31 to 8,811,588 at June 30, a 9.1% reduction. MOZAYYX UGP, which filed a 13D the same day at 9.99% including strategic-advisor warrants from the placement, has not amended since.
- Own calculation (13F tables, 20 investors): Berkshire Hathaway, Bridgewater, Renaissance, Soros, Duquesne, Pershing Square, Third Point, Baupost, Appaloosa, Greenlight, Scion, Tiger Global, Coatue, Lone Pine, Viking, Elliott, Icahn, Two Sigma and Paulson did not hold BMNR in their June 30, 2026 tables. Of the six that did, all but ARK are multi-strategy hedge funds, and their common-stock holdings together are 2.5%.
- No Korean company has invested; a search of 78 filing bodies, the proxy and every 13D/G for Korean corporate names found none. Korean individuals are a different story.
- Outside view (Digital Today report, January 2026): Citing Bloomberg's compilation of Korea Securities Depository data, Korean retail investors net bought about $1.4 billion of Bitmine in 2025, second only to Alphabet, plus $566 million of a 2x leveraged ETF. In the single month from July 4 to August 4, 2025 the net purchase was $253.47 million, the most of any foreign stock.
- Outside view (Money Today report, August 2026): A year on, the top net-buy slot has passed to a 3x semiconductor ETF, whose one-month net purchases were 8.1 times Bitmine's a year earlier. The company maintains a Korean-language press-release page and issues its weekly holdings release in Korean as well as English.
- Half the management team turned over in a year. Founder Jonathan Bates handed the chairman's seat to Tom Lee on June 30, 2025 and the CEO seat on November 14, and does not appear among the eight director nominees at the January 2026 meeting. CFO Raymond Mow signed a separation agreement on December 11, 2025 and left January 16, 2026. President Erik Nelson was terminated "without cause" on January 22, 2026 with $585,000 of severance. There have been 15 8-K Item 5.02 filings and 32 Form 4 insider filings in the last twelve months. New CEO Chi Tsang ran Asia TMT global banking at HSBC and later founded the venture fund m1720; the CFO and COO is Young Kim.
- Outside view (Decrypt and CoinDesk reports, November 2025): Both framed the appointment as Tom Lee's Ethereum treasury replacing its founder-CEO with an investment banker. TheStreet's headline the same day read "Wall Street legend backed stock slumps after new CEO appointment."
- The January 15, 2026 annual meeting is the record of how shareholders see this team (January 20, 2026 8-K).
| Proposal | For | Against or withheld | Approval |
| Executive chairman special performance award (advisory) | 140,246,624 | 39,301,665 against, 5,590,890 abstain | 78.1% |
| Authorized shares from 500 million to 50 billion | 222,226,997 | 49,445,035 against | 81.8% |
| 2025 Omnibus Incentive Plan | 164,207,516 | 14,360,681 against | 92.0% |
| Director Thomas Lee | 182,066,768 | 3,072,442 withheld | 98.3% |
| Director Lori Love | 175,038,565 | 10,100,645 withheld | 94.6% |
- Filing footnote (proxy statement, award table): The chairman's performance shares sit in six cells: 500,000 shares at a 4% share of ETH supply and 1,000,000 at 5%; the same quantities at a $125 and a $250 share price; and the same again at a $25 billion and a $50 billion market capitalization, up to 4.5 million shares in total. The 4% cell is already met; the $125 cell is five times the current price, and the $25 billion cell is 1.66 times the current market cap.
- One shareholder in five voted against the chairman's award on the same day four in five approved a hundredfold increase in the shares the company may issue. Authorized shares are a ceiling rather than a plan, but next to the $24.5 billion ATM capacity they define how much stock the company can sell when it chooses to.
Bitmine vs Direct ETH and Other Crypto Treasuries
- The market calls companies like this digital asset treasuries. They sell stock and bonds, buy a coin with the proceeds, and let the coin's price set the share price. Strategy (formerly MicroStrategy) started it with Bitcoin in 2020, and since summer 2025 the format has split into Ethereum, Solana and Hyperliquid versions.
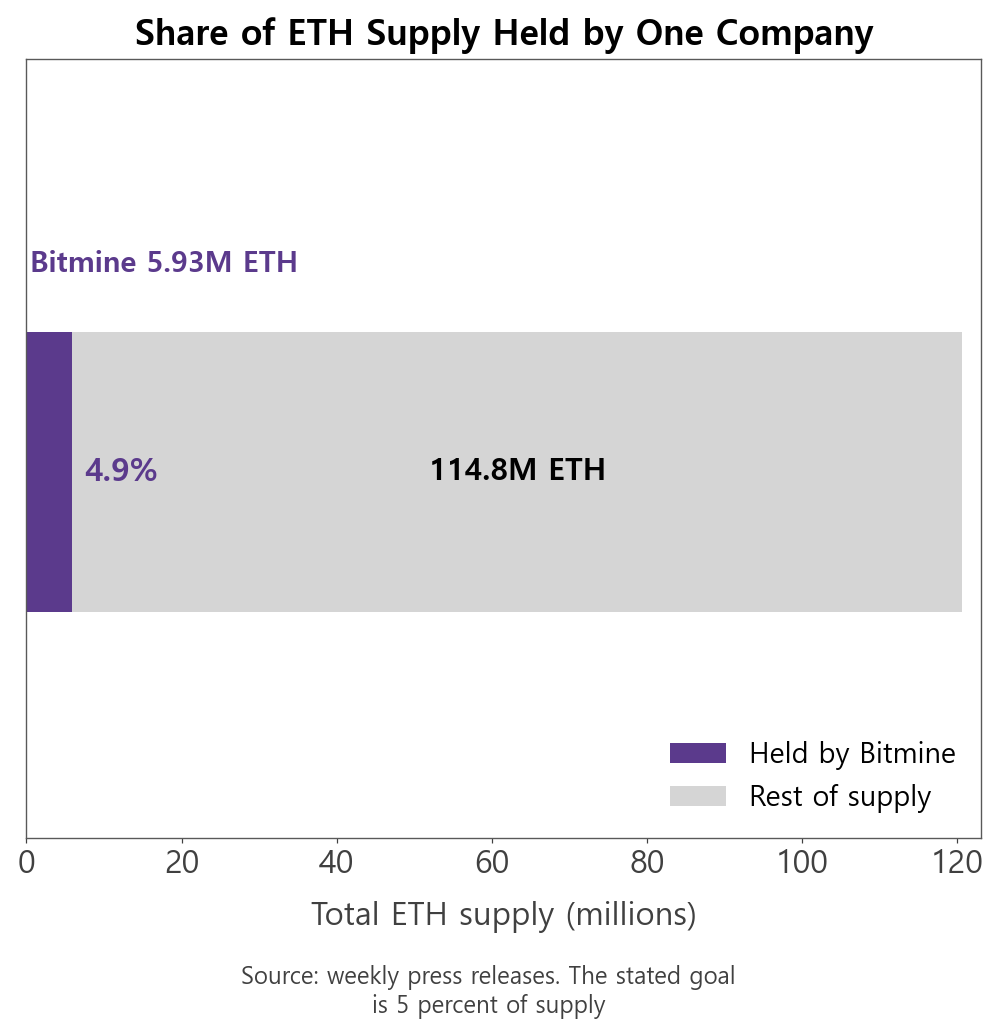
- A sector growth rate cannot be computed: the Ethereum branch is fifteen months old, and the treasury growing from $250 million to $15.7 billion, 63 times, is one company's issuance velocity rather than an industry statistic. The number of competitors is not in filings either; the 10-K's competition paragraph names "other digital asset treasury companies, ETFs and direct ownership" in general terms. The one share figure that can be calculated is 4.9% of a supply worth $301 billion at $2,495.
- Buying ETH directly and buying this stock differ in three ways. Buying directly, you get one coin for the price of one coin. Buying the stock at today's ratio, you get the coins plus cash, venture stakes and staking income for about 0.96 times the coin value, after the company deducts $26.6 million a year of preferred dividends and its asset management fees. And the price at which the company sells new shares changes your per-share slice, a variable that direct ownership does not have.
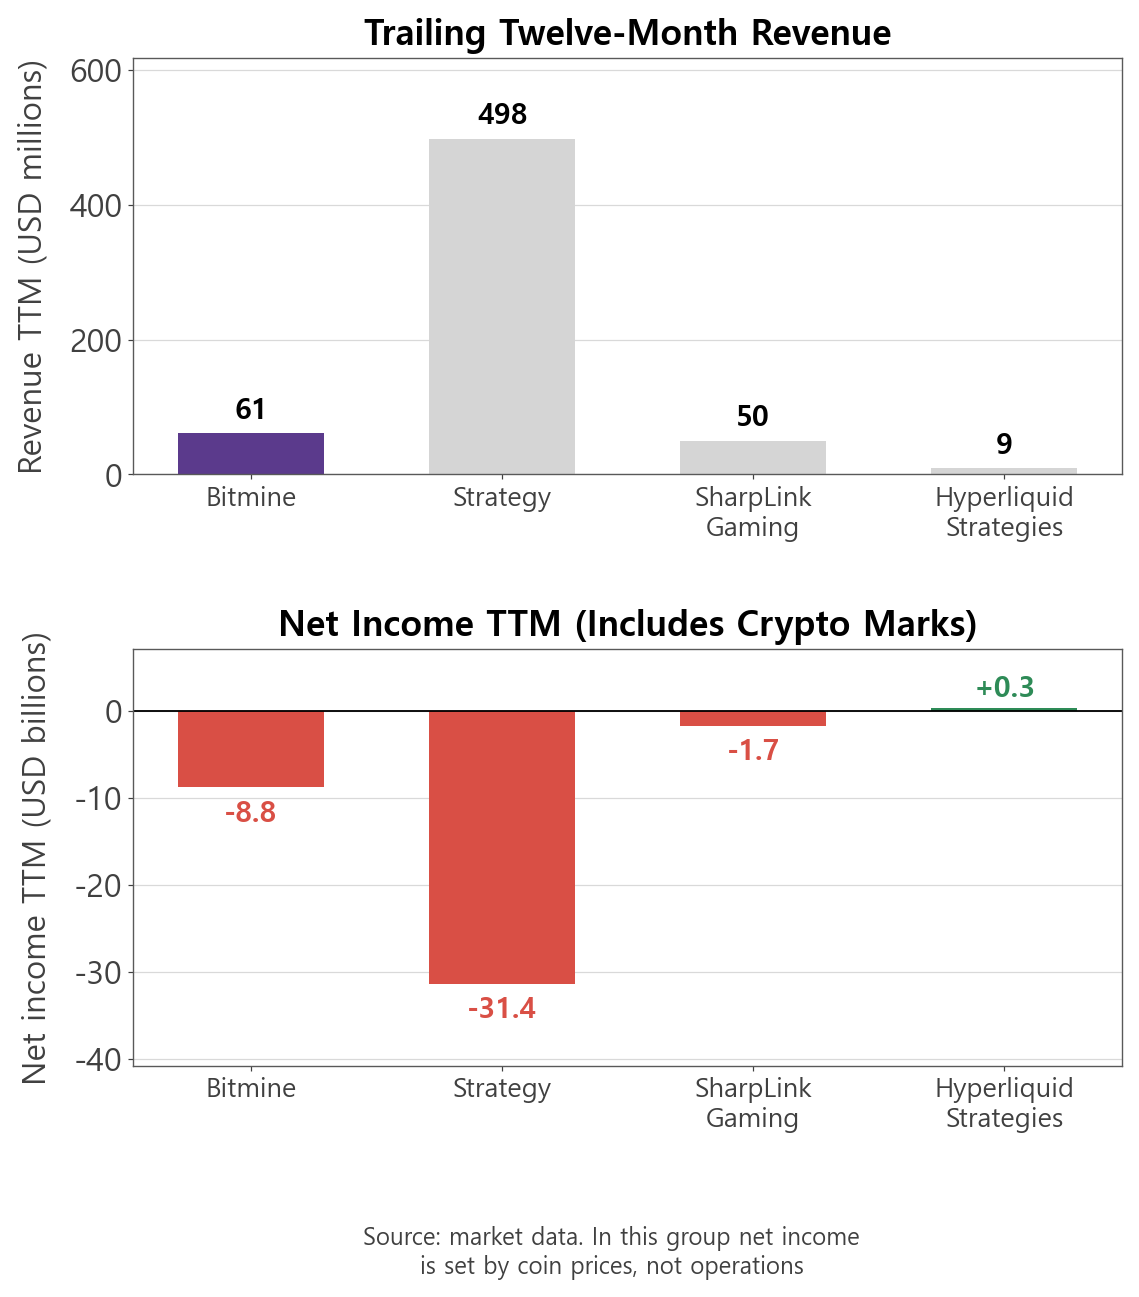
- Against listed companies that buy coins the same way, on trailing-twelve-month aggregator figures:
| Company | Ticker | Asset held | Market cap | P/B | P/S | Revenue (TTM) | Net income (TTM) |
| Bitmine | BMNR | 5.93 million ETH | $15.1 billion | 1.25x | 246.7x | $61.2 million | -$8.77 billion |
| Strategy | MSTR | Bitcoin | $50.3 billion | 1.58x | 101.0x | $498.35 million | -$31.37 billion |
| SharpLink Gaming | SBET | Ethereum | $1.9 billion | 1.37x | 38.4x | $50.2 million | -$1.71 billion |
| Hyperliquid Strategies | PURR | HYPE | $2.3 billion | 1.24x | 243.1x | $9.46 million | +$256.18 million |
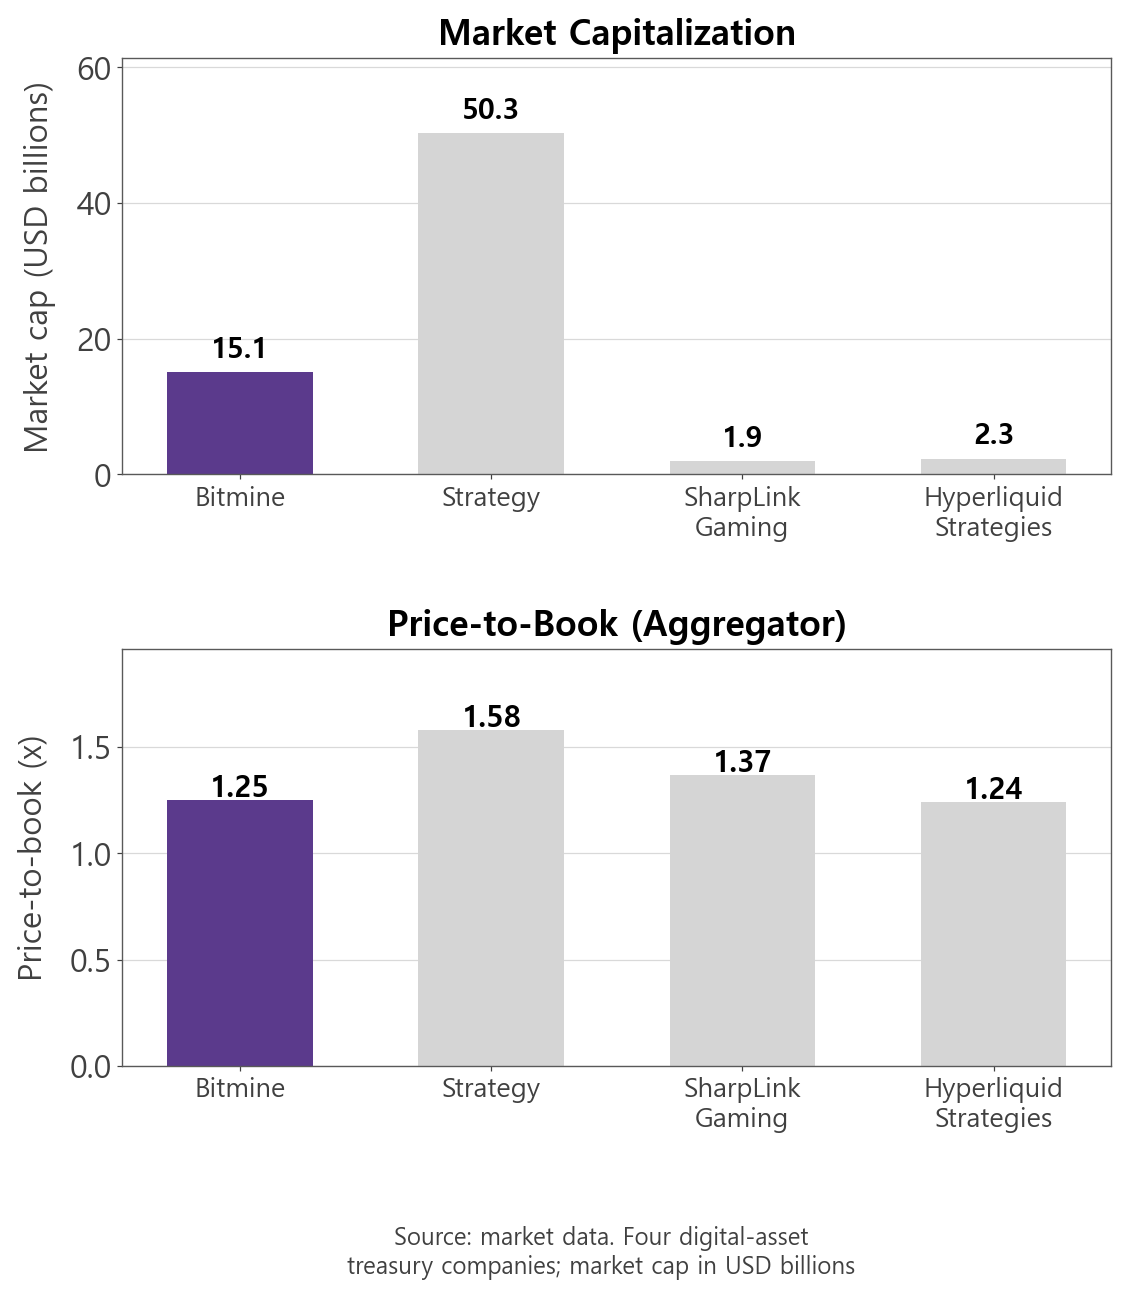
- None of the four has a net income figure that describes its business. Strategy's -$31.37 billion and Bitmine's -$8.77 billion are unrealized marks on coins nobody sold, and Hyperliquid Strategies' +$256.18 million is the same thing pointed the other way; a P/S of 246.7x is meaningless for the same reason. So the group gets compared on whether the coin pays a yield, what the market pays over book, and what the company gives back. The multiple in the next table is the aggregator P/B on book equity, a different metric from the 0.96 on reported assets used earlier.
| Company | Yield on the coin | P/B (book equity) | Shareholder payout | Funding |
| Bitmine | Staking, 2.61%, 85.5% staked | 1.25x | Common $0.01; preferred 9.50% | $24.5 billion ATM capacity; preferred |
| Strategy | None (Bitcoin) | 1.58x | Four preferred series | ATM, converts, preferred |
| SharpLink Gaming | Staking | 1.37x | None | ATM |
| Hyperliquid Strategies | Staking | 1.24x | None | Merger proceeds |
- Bitcoin pays nothing for being held, which is why Strategy is loss-making at the operating line with 840,000 coins. Ethereum is proof-of-stake, so deposited coins earn rewards, and the ETH camp looks at staking ratio before holdings. Bitmine's 85.5% is the highest in the table, and the reward rate is still not the company's to raise.
- Regulation runs on two tracks in the company's own deck. The Clarity Act sat at a 44% probability on slide 11, with the chairman relaying that "Coinbase's vice chairman thinks we're at the one-yard line" and that Senator Lummis believes "they're going to land the plane." The August 24 release compared the GENIUS Act and the SEC's Project Crypto to the 1971 exit from the gold standard. Neither act contains a clause that touches this company's revenue.
BMNR Stock Outlook: What Would Move the Price
Five Conditions to Watch
| Indicator | What keeps the case alive | What breaks it | When and where to check |
| Market cap ÷ weekly reported assets | Back above 1.05, where new shares add assets per share | Below 0.95 for weeks, with ATM sales resumed in that state | Weekly Monday 8-K |
| ETH per share | Around 0.00983 at the August 31 year-end | Below the May 31 figure of 0.009345 | Annual report (10-K) in November |
| Weekly ETH purchases | The remaining 105,802 ETH to 5% bought with capital raised above a ratio of 1 | Under 10,000 a week for months | Weekly 8-K |
| Staking revenue and management fees | Above $50 million a quarter; fees inside the $40 to $50 million twelve-month guide | A new fee recipient appears after the Ethereum Tower termination | November 10-K; transition report in early 2027 |
| Holdings of named investors | ARK and Vanguard hold | ARK trims again; Vanguard drops below 5% | 13F filings in November (September 30 positions) |
- The thresholds are chosen this way. 1.05 and 0.95 bracket a ratio of 1 by more than typical ATM fees of 2% to 3% and the noise in a weekly asset tally. 0.009345 ETH per share is the last disclosed value and 0.00983 is the ceiling computed on the July share count, so where the November 10-K lands between them answers whether issuance added to or subtracted from each holder's slice. 10,000 ETH a week is August's low, and $50 million of quarterly staking revenue is the FQ3 $45.74 million plus growth in the staked balance.
- The outlook is the combination of those conditions. If ETH rises, the stock follows at roughly the 0.010 coefficient, and the company's method of adding to per-share holdings through issuance only restarts once the ratio is back above 1. If ETH falls, the ratio tends to stay below 1 as it is now, and issuance in that state reduces existing holders' assets per share. In the three weeks after August 26 the company bought 81,587 ETH with the ratio below 1 throughout.
What Would Change the Call
| Scenario | Condition | Indicator to check | When · Source |
| Upside | ETH clears the deck's $2,225 level and holds; ratio back above 1.05 | Weekly reported assets vs market cap | Weekly 8-K |
| Upside | ETH per share at the August year-end prints above 0.009345 | Cover-page share count and holdings | 10-K in November |
| Downside | ATM issuance resumes with the ratio under 1 | Share count in the 10-K vs the July cover page | 10-K in November |
| Downside | Staking yield compresses as network-wide staking rises | Company's seven-day yield disclosure | Weekly 8-K |
| Multiple risk | The Clarity Act fails or stalls into 2027 | Prediction-market odds the company itself cites | Deck updates; Chairman's Message |
- One question this article could not answer. The 10-Q carries $6.71 million of accrued "digital asset management fees," and the company guided twelve-month asset management fees at $40 to $50 million. The counterparty to both the July 8, 2025 consulting agreement and the March 24, 2026 staking management agreement is Ethereum Tower LLC, which also owns 2% of MAVAN Holdings. The staking agreement ended on September 3; the filings do not say what happened to the consulting agreement, and no filing names a principal of Ethereum Tower. Who receives $40 to $50 million a year, and what is that company's relationship to the chairman or the board? Will the related-party note in the November 10-K print a name?
Related Analysis
- lululemon (LULU) Stock Analysis: Margin Decline and Tariffs
- Dell (DELL) Stock Analysis: Q2 FY2027 Earnings and Guidance
Methodology and Sources
- Share price is $25.03 and market capitalization uses the 603,226,394 common shares on the cover of the fiscal Q3 2026 Form 10-Q (cover date July 9, 2026); shares sold through the ATM since that date will appear in the next report. ETH holdings, staked ETH and total assets come from the September 8 weekly 8-K press release (September 7 basis); equity, liabilities and ETH per share are from the May 31, 2026 quarterly report. I downloaded and parsed all 100 weekly 8-K press releases from the SEC filing index into a holdings, purchase and sentence-presence time series. Five-year financials are 10-K XBRL values; the five largest daily moves are drawn from 318 daily closes since listing. Ownership comes from the DEF 14A proxy, Schedule 13D/G filings and the 13F tables of 20 named investors, read directly from EDGAR. The two investor decks are the originals on the company's investor relations page; the June 30, 2025 8-K is the pivot filing.
- Outside views come from Cantor Fitzgerald research (September 2026), Decrypt, CoinDesk and TheStreet coverage (November 2025), Digital Today (January 2026) and Money Today (August 2026) reporting, and an investor-community forecast post (June 2026); every number from those sources was rechecked against filings and anything that could not be checked is marked unverified in the verdict table. Consensus figures are aggregated sell-side estimates. This analysis is based on public filings and is not investment advice.
#Bitmine #BMNR #BMNRStock #BMNRStockAnalysis #Ethereum #DigitalAssetTreasury #ETHStaking #USStocks #StockAnalysis #EquityResearch #GlobalStockBrief
'US Stock Analysis' 카테고리의 다른 글
| Plug Power (PLUG) Stock Analysis: GAAP vs Operating Loss (0) | 2026.09.15 |
|---|---|
| Trip.com (TCOM) Stock Analysis: Antitrust Fine and Guidance (0) | 2026.09.14 |
| Sumitomo Electric (5802) Stock Analysis: Data Center Optics (0) | 2026.09.13 |
| Oracle (ORCL) Stock Analysis: Cash Flow and Capex Gap (0) | 2026.09.12 |
| Linde (LIN) Stock Analysis: Price, Volume and Margin Trends (0) | 2026.09.12 |


