💡 Today's US market in three lines
① Today's three stocks: Tempus AI · Caris Life Sciences · Intel — an AI diagnostics platform, a molecular profiling lab, and a chipmaker that all closed sharply higher on the day the market took back what the Fed took away.
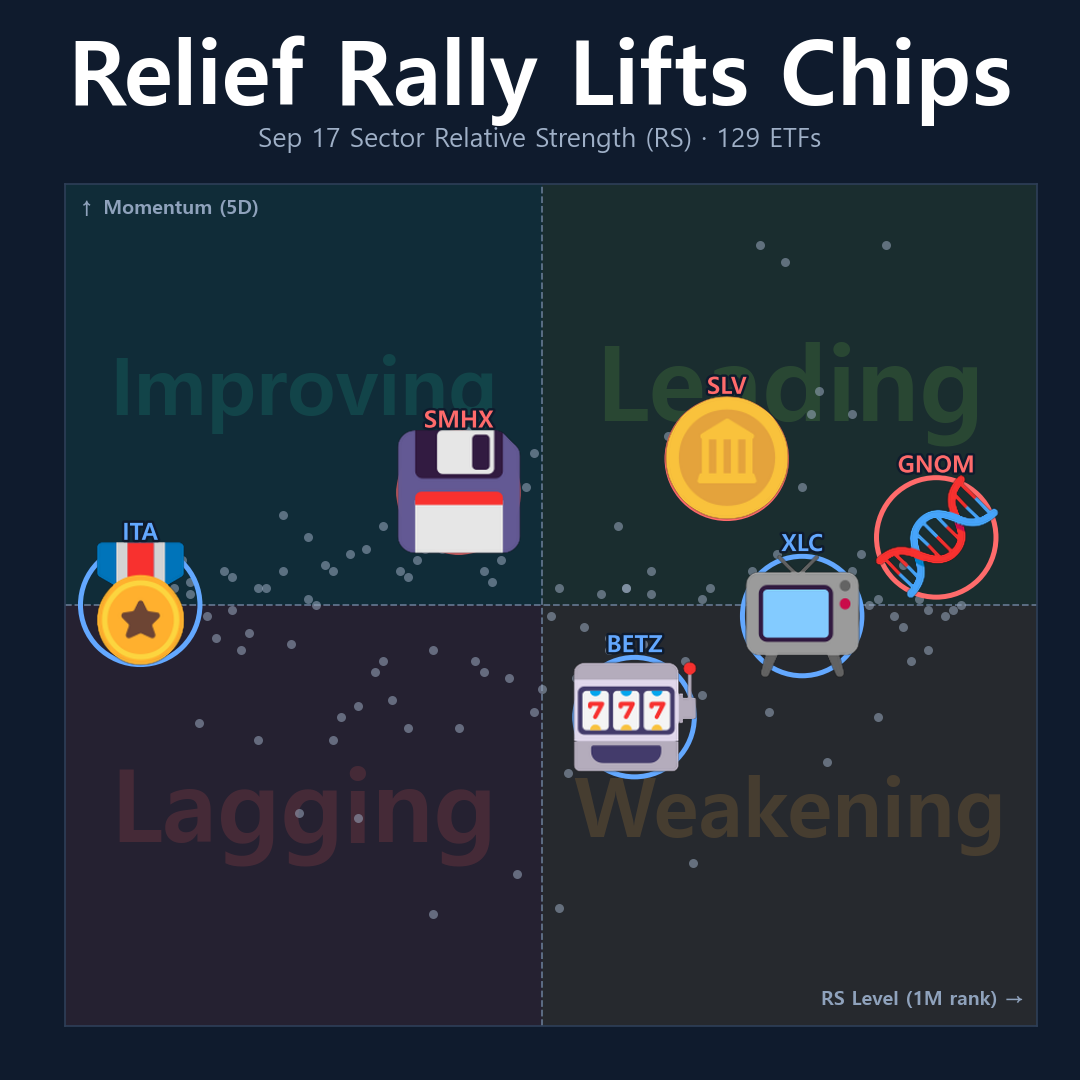
② On September 17, the S&P 500 closed +1.14% at 7,637.76 and the Nasdaq added 1.69% to 26,418.30. Of the 129 ETFs in our universe, 115 rose and 13 fell, and 9 of the 11 sector SPDRs finished green.
③ Bond yields eased, oil slipped, and the volatility index fell -12.82% to 15.44. Chips, genomics, silver miners, and blockchain all posted the kind of gains that only show up when risk appetite turns at once.
Today's Sector Relative Strength (RS)
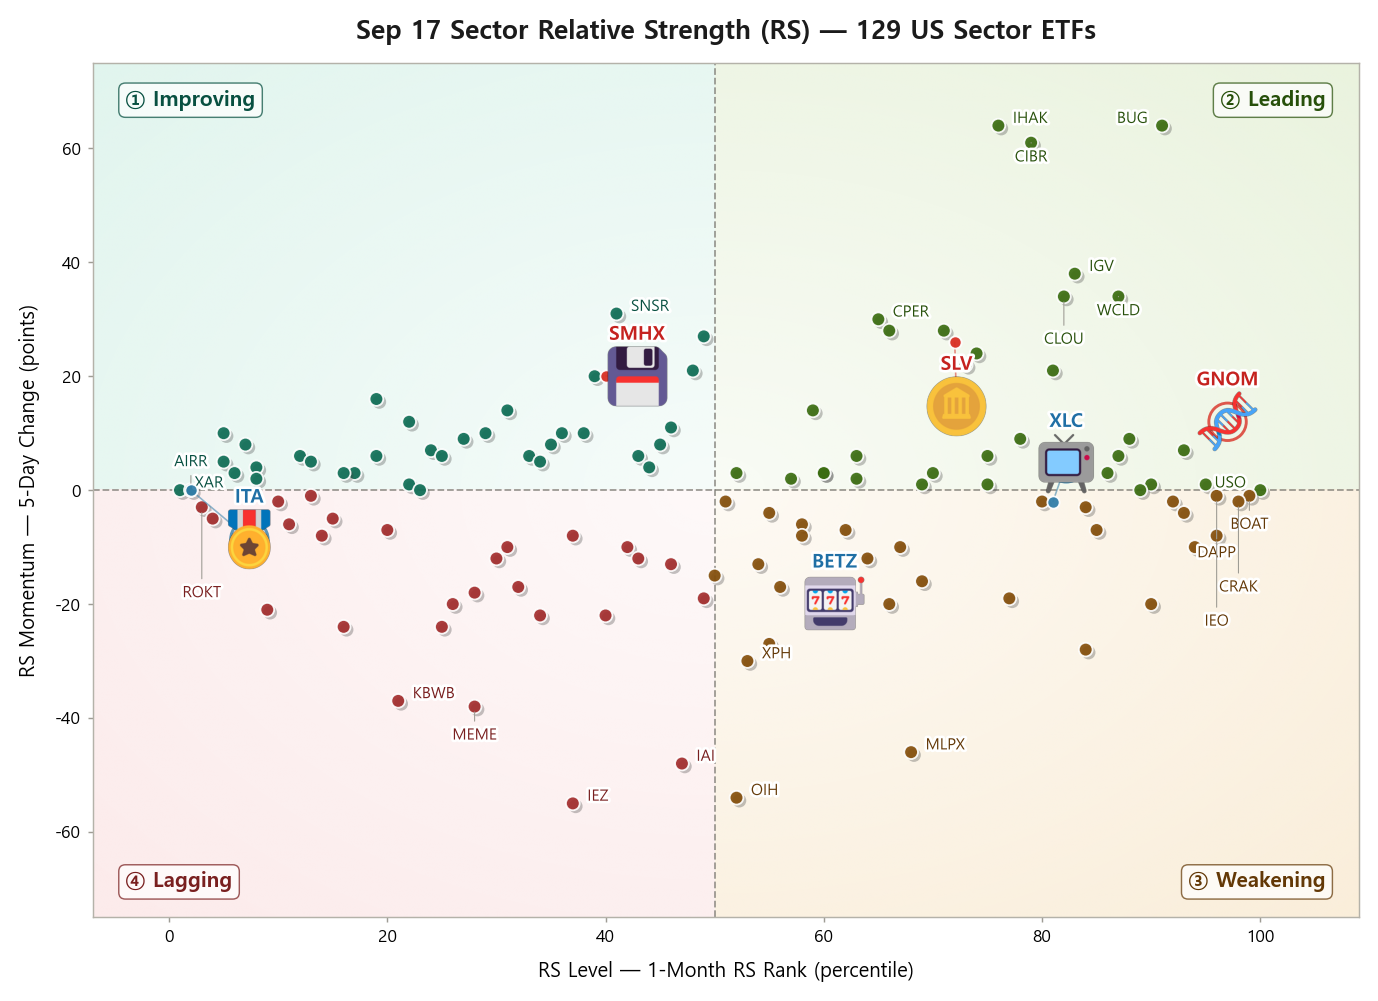
- One day after the Fed lifted rates for the first time in three years, buyers came back for almost everything they had sold. The 10-year Treasury yield slipped to 4.95% from 5.01%, crude eased, and the sell-off in front of Chair Kevin Warsh's press conference turned out to be a single session rather than a trend. By Thursday the hike read as an inflation fix, and that reading was enough.
- The S&P 500 closed +1.14% at 7,637.76, the Nasdaq +1.69% at 26,418.30, and the Dow +0.61% at 51,778.04. Growth led value again: the Russell 1000 Growth ETF (IWF) gained +1.65% against +0.66% for the Russell 1000 Value ETF (IWD), and the Nasdaq-100 fund (QQQ) added +1.73%. The equal-weight S&P 500 (RSP) rose only +0.49% and small caps (IWM) +0.53%, so the index once again beat the average stock. Technology (+2.25%) was the strongest sector SPDR by a wide margin, and only communication services (-0.58%) and financials (-0.09%) finished red.
- Chips did the heavy lifting. The iShares semiconductor fund (SOXX) rose +3.39%, fabless semiconductors (SMHX) +3.69%, and AI semiconductors (CHPX) +3.65%. Micron gained +5.50% after Intel chief executive Lip-Bu Tan told an industry audience that memory demand is not slowing and prices should keep rising. AMD added +6.36%, Skyworks +6.69%, and Taiwan Semiconductor +3.00%. Precious metals ran alongside them. Silver miners (SIL) gained +4.49%, junior gold miners (GDXJ) +4.75%, and the silver trust (SLV) +3.37% as bullion recovered the ground it lost on Fed day. Oil was the one asset that did not join in: WTI settled at $101.09, down -1.31%, and Brent at $104.09, down -1.64%.
Today's Leading Sectors TOP 5
- Basis: top 5 by 1-month RS rank on the 'Sector RS (US)' sheet — 129-ETF universe, September 17, 2026. Daily moves are measured from Yahoo closing prices. Trend columns compare price to its 1-month, 1-quarter, and 1-year moving averages.
| ETF | 1-Day | RS Rank 1M | Short-Term | Mid-Term | Long-Term |
| United States Oil Fund (USO) | -0.55% | 100 | 🔺 | 🔺 | 🔺 |
| SonicShares Global Shipping (BOAT) | +1.69% | 99 | 🔺 | 🔺 | 🔺 |
| VanEck Oil Refiners (CRAK) | +1.87% | 98 | 🔺 | 🔺 | 🔺 |
| Global X Genomics and Biotechnology (GNOM) | +5.25% | 97 | 🔺 | 🔺 | 🔺 |
| VanEck Digital Transformation (DAPP) | +3.70% | 96 | 🔽 | 🔺 | 🔺 |
- The oil complex still holds the top of the table, but its grip is loosening. USO is +18.87% over the past month, which is why a fourth straight down session leaves the rank untouched, yet the fund has now lost -1.94% over five days. Shipping and refining, the two businesses that earn on moving and processing crude, both closed higher. The newcomers are the interesting part: genomics entered the top five for the first time this month, and blockchain equities sit a point behind with iShares oil and gas exploration (IEO) also at 96.
Why They're Strong — Sector Issues
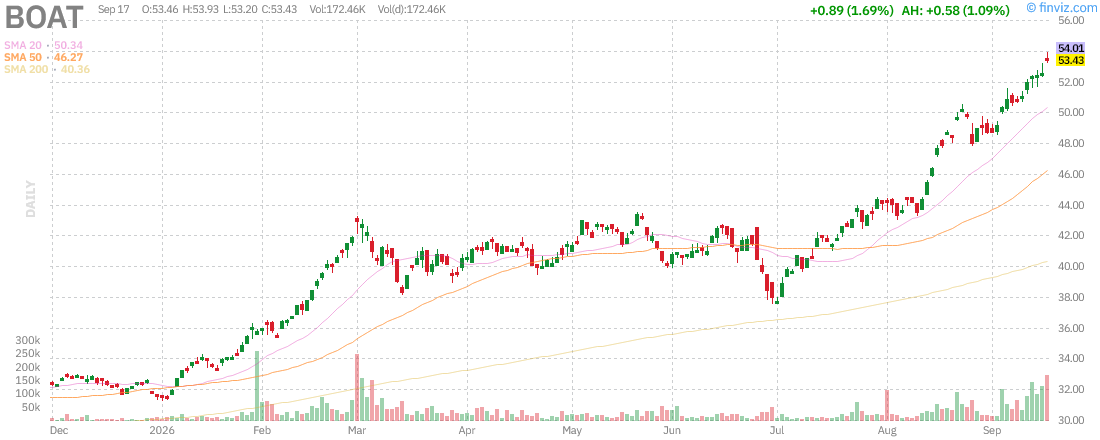
· Shipping and refining (BOAT · CRAK) — Tankers keep working while barrels get cheaper. BOAT rose +1.69% and is +4.70% over five sessions, against -1.94% for crude itself. Okeanis Eco Tankers gained +1.84% and is +18.35% over the same week, and Frontline added +0.67%. Refiners follow a different lever: CRAK rose +1.87% because cheaper input crude widens the crack spread that refining margins are built on. Both groups gain from the Saudi pipeline disruption that is rerouting barrels onto longer voyages.
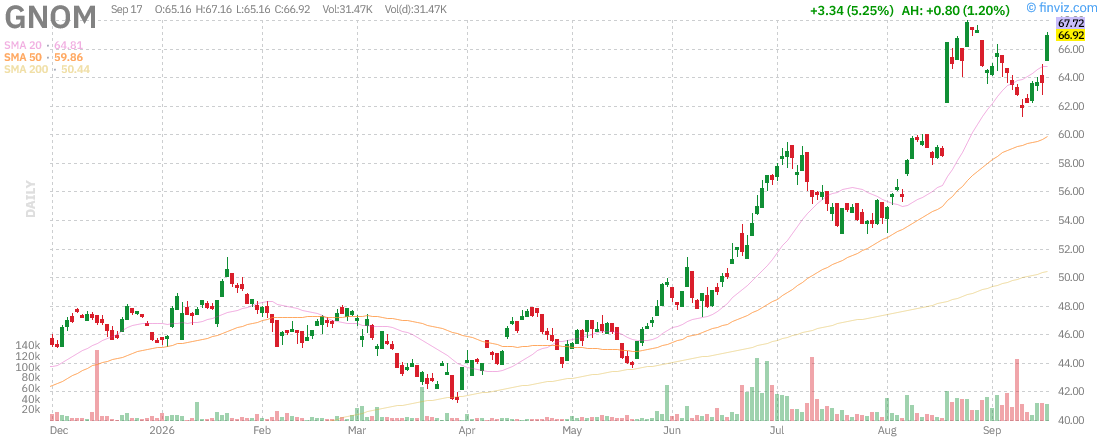
· Genomics (GNOM) — Up +5.25%, the best single-day move in the universe, and now +14.38% for the month. Moderna, the fund's largest holding, gained +8.55% and is up more than 150% in a month on its melanoma cancer vaccine data with Merck. Illumina rose +7.10% ahead of its scheduled return to the S&P 500 on September 21. GeneDx added +7.73%, 10x Genomics +5.90%, and Natera +6.07%. What makes this different from a headline pop is breadth: sequencing hardware, rare-disease testing, and oncology diagnostics all moved together.
1-Month RS Trend

- The 45-day chart follows five of today's RRG heroes and shows two clean reversals. Genomics (GNOM) fell from the mid-90s in July to 14 in early August, then climbed back to 99 — a full round trip in six weeks. Silver (SLV) traced the opposite shape, holding above 90 through late August before a September slide and this week's recovery to 82. Fabless semiconductors (SMHX) spent almost the entire window under 40 and only now reached 58. The two lines falling off the right edge are the energy and financial trades: oil services (OIH) gave back -54 points in five sessions and brokers (IAI) -48.
RS Breakdown Warnings (big 5-day drops)
· Oil equipment and services (IEZ) lost -55 points in five trading days, the steepest drop in the universe. Oil services (OIH) fell -54 points, brokers and exchanges (IAI) -48, natural gas producers (FCG) -28, and nuclear power (NLR) -24.
· Two trades are unwinding at the same time. One is the oil service complex that was priced for crude above $100 and is now watching the Saudi outage get repaired. The other is anything that borrows to build, from nuclear utilities to brokers, which a 10-year yield near 5% makes more expensive.
RS Rebound Signals (sharp bounces off the bottom)
· Cybersecurity (BUG) rebounded +64 points in five sessions, the largest recovery in the universe. iShares Cybersecurity (IHAK) added the same +64 points and First Trust Cybersecurity (CIBR) +61.
· Behind the security names, the rebound list leans industrial and technological. Video games (ESPO) gained +28 points, materials (XLB) +21, and autonomous technology (ARKQ) +20. Money that left energy and metals last week has landed in software and manufacturing.
Today's Top Rising Sectors TOP 5 (by 1-day %)
- Basis: top 5 by September 17 closing move — 115 of 129 rose on the day. RS ranks from the 'Sector RS (US)' sheet.
| ETF | 1-Day | RS Rank 1M | Short-Term | Mid-Term | Long-Term |
| Global X Genomics and Biotechnology (GNOM) | +5.25% | 97 | 🔺 | 🔺 | 🔺 |
| VanEck Junior Gold Miners (GDXJ) | +4.75% | 86 | 🔽 | 🔺 | 🔺 |
| Global X Silver Miners (SIL) | +4.49% | 87 | 🔽 | 🔺 | 🔺 |
| Global X Blockchain (BKCH) | +4.27% | 95 | 🔺 | 🔺 | 🔽 |
| Roundhill Meme Stock (MEME) | +4.01% | 28 | 🔺 | 🔺 | 🔺 |
- This is a risk-appetite list, not a defensive one. Four of the five carry RS ranks above 85, which separates today from the kind of session where only beaten-down funds bounce. Meme stocks are the exception at rank 28, and their presence alongside miners and blockchain is the clearest sign of what changed: the same money that fled on Fed day came back for the highest-beta corners of the market first.
Why They Rose — Sector Issues
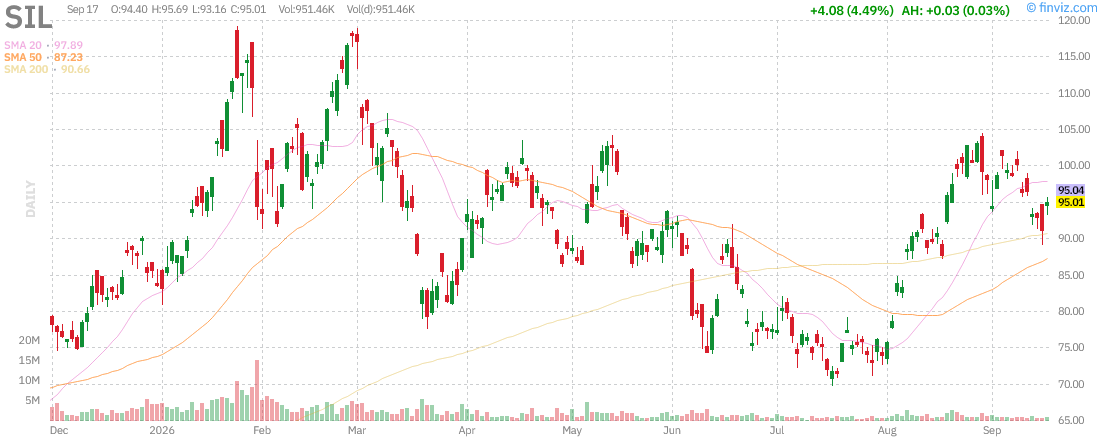
· Silver and gold miners (SIL · GDXJ) — Silver miners rose +4.49% and junior gold miners +4.75%. Bullion led the way, with silver futures settling +2.22% at $65.71 and the gold trust (GLD) up +1.69%, both recovering what they surrendered when the Fed decision landed. The miners amplified it, as they always do: First Majestic gained +6.33%, Hecla +5.39%, Coeur +5.27%, and Pan American Silver +4.33%. A 10-year yield that stepped back from 5% lowers the cost of holding metal that pays no coupon.
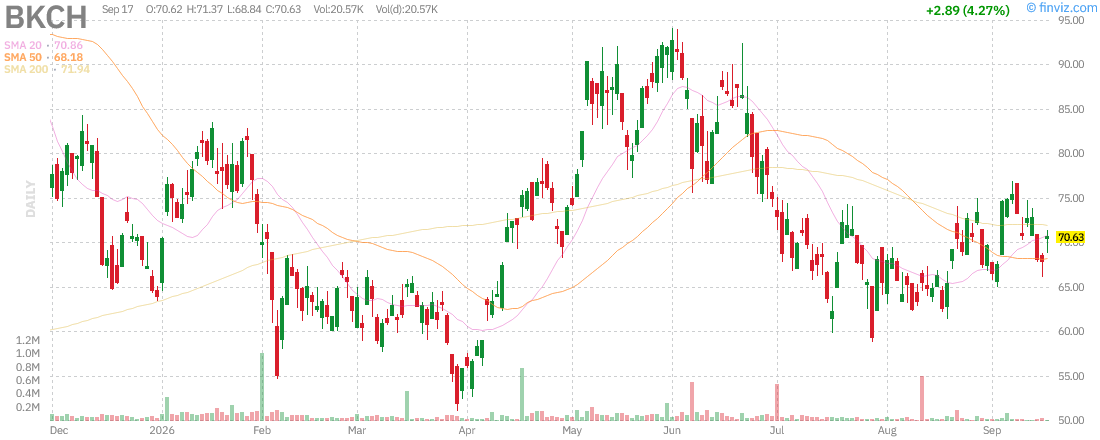
· Blockchain and digital assets (BKCH · DAPP · NODE) — Blockchain equities rose +4.27%, digital transformation +3.70%, and onchain economy +3.38%. Riot Platforms led the miners at +7.52%, Coinbase gained +5.75%, Marathon +5.43%, and Strategy +4.81%. These names carry the highest beta to liquidity expectations in the universe, so a session that reprices the rate path shows up here first. Note the divergence in the trend columns, though: BKCH still trades below its 1-year moving average.
Leading Sectors: Shipping, Genomics, Silver
- ① The market decided the hike was aimed at inflation, and bought the cyclical side of the tape. Semiconductors, miners, and blockchain equities led while the two sectors most exposed to the discount rate — communication services and financials — stayed red. The rebound had a shape, and the discount rate drew it.
- ② Shipping now looks like the most durable part of the energy trade. BOAT holds RS 99 while crude itself has lost -1.94% over five sessions, and oil services have collapsed -54 points in the same window. Tanker owners collect day rates on voyage length, and the Saudi rerouting is lengthening voyages regardless of what a barrel costs. Producers and service companies need the price; ships need the distance.
- ③ Genomics arrived at the top of the table with a different engine. GNOM holds RS 97 and trades above all three moving averages, and its move runs across sequencing tools, rare-disease testing, and oncology diagnostics. One drug result did not do this. Silver miners, by contrast, still sit below their 1-month average despite today's +4.49%, which marks them as a bounce inside a correction.
- ④ The last report covered the September 16 close. Its three picks, measured from that close to Thursday: Twist Bioscience +8.73%, DHT Holdings -0.95%, and SailPoint -0.83%. The S&P 500 returned +1.14% over the same session, so one of the three beat the index and two lagged it. Twist rode the same genomics wave described above, while the tanker and identity-security picks went sideways on a day the market bought beta. Recorded as is.
Today's Three Stocks — Tempus AI · Caris Life Sciences · Intel Stock Forecast
- Selection: from the 1,146 stocks held by the universe's ETFs — RS 1D≥60 & 5D≥75 & 1M≥85, with all three moving averages aligned (▲▲▲)
Tempus AI (TEM) — 1-Month RS 100: Reimbursement Math Rewrites the Model
| RS 1D | RS 5D | RS 1M | 1M Return | Held By |
| 100 | 100 | 100 | +62.8% | Global X Telemedicine and Digital Health |
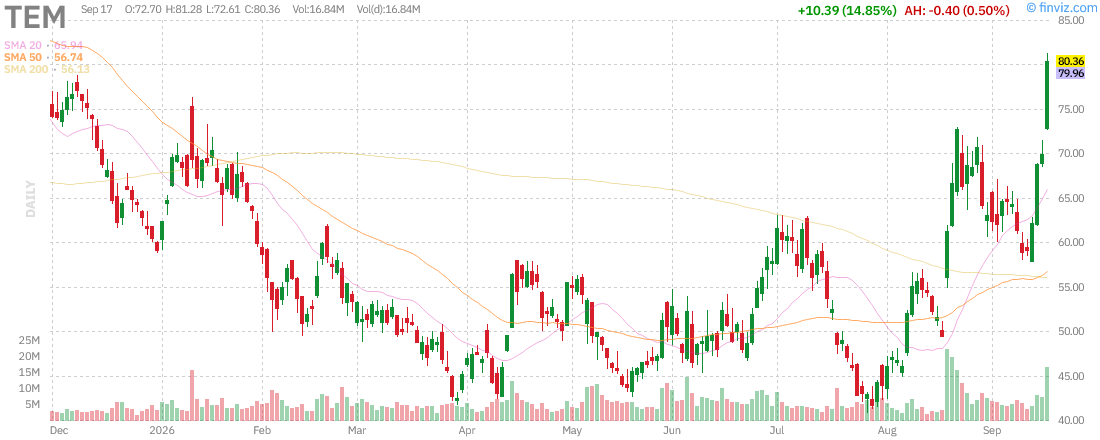
- Up +14.85% to $80.36, the biggest move among the stocks that cleared the screen, and +36.81% over five sessions. Tempus runs a diagnostics business and a data business side by side: it sequences tumors and then licenses the resulting library to drug developers. Second-quarter revenue rose 22% to $382.5 million, with diagnostics at $289.3 million on 31% oncology volume growth and data and applications at $93.2 million. Net income of $5.6 million reversed a $42.8 million loss a year earlier, and full-year guidance was raised to $1.595–1.605 billion with roughly $65 million of adjusted EBITDA. This week's move came from a Morgan Stanley analysis on September 15 arguing that reimbursement pricing on the xT and xF tests could add $330–400 million of annual revenue. The Tempus AI stock forecast depends on whether that reimbursement math shows up in reported revenue, because a stock that has run 62.8% in a month is already paying for it.
Caris Life Sciences (CAI) — 1-Month RS 100: Molecular Profiling at 45% Growth
| RS 1D | RS 5D | RS 1M | 1M Return | Held By |
| 99 | 100 | 100 | +47.4% | Global X Genomics and Biotechnology |
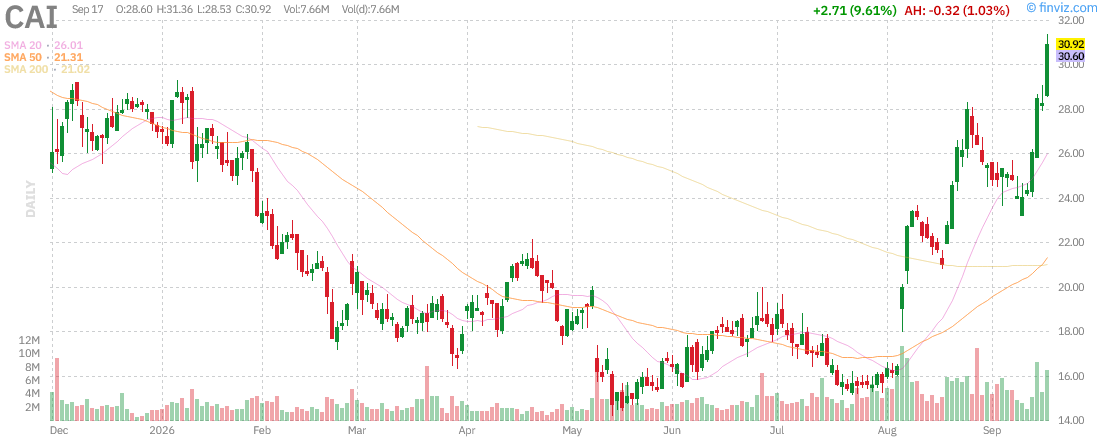
- Up +9.61% to $30.92, adding to a +28.62% five-day run, and one of the genomics names that carried GNOM to the top of the RS table. Caris profiles tumors at the molecular level and matches them to therapies, which puts it in direct competition with the company above. Second-quarter revenue rose 45% to $263.7 million, led by 55% growth in molecular profiling services to $252.3 million, on roughly 59,200 clinical cases. Gross margin improved about 500 basis points to 68%, and adjusted EBITDA came in positive at $55.7 million. Management raised full-year guidance to $1.03–1.04 billion, up from $1.00–1.02 billion, for growth of 27% to 28%. The Caris Life Sciences stock forecast rests on the newer Caris Assure blood test, which accounted for roughly 10,700 of those cases. Volume growth of 18% against revenue growth of 45% says the price per case is still rising, and that gap is what the valuation is extrapolating.
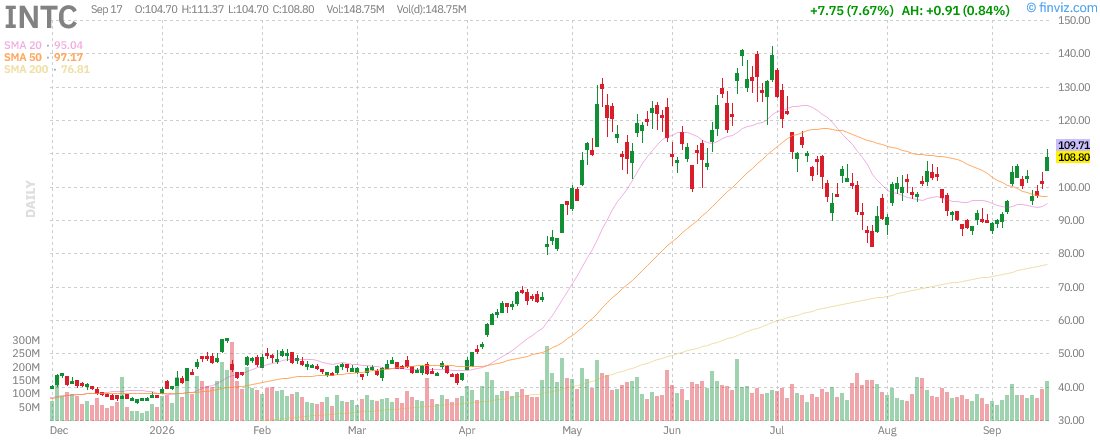
Intel (INTC) — 1-Month RS 93: Foundry Bet Finds a Memory Customer
| RS 1D | RS 5D | RS 1M | 1M Return | Held By |
| 98 | 95 | 93 | +12.5% | iShares Semiconductor · VanEck Semiconductor · Global X AI Semiconductor |
- Up +7.67% to $108.80 on reports that SK Hynix is in early talks to have Intel manufacture memory chips in the United States, likely at the planned Ohio site. SK Hynix confirmed it is exploring a US memory partnership while stressing that nothing is settled, which is the right way to read it: this is a rumor with a long runway, not a signed contract. The underlying numbers are firmer. Second-quarter revenue of $16.1 billion beat the guidance midpoint by $1.8 billion, non-GAAP gross margin came in at 41.8%, and non-GAAP earnings of $0.42 per share doubled the $0.20 guide. Data center AI revenue reached $6.3 billion, up 59% from a year earlier, and 2026 capital spending guidance was raised above $20 billion on customer demand. External foundry revenue, however, was only $293 million in the quarter. The Intel stock forecast turns on closing that gap, and a memory customer of SK Hynix's size would be the first real proof that the foundry strategy works.
Tempus AI · Caris Life Sciences · Intel Stock Forecast Checkpoints
· Tempus AI stock forecast — The rerating is built on an analyst's reimbursement model. Reported revenue has yet to confirm it. Watch whether third-quarter diagnostics revenue per test moves up. That is where higher reimbursement would appear first.
· Caris Life Sciences stock forecast — Revenue is growing more than twice as fast as case volume. Watch whether Caris Assure case counts keep climbing next quarter. The blood test is what turns a profiling lab into a screening business.
· Intel stock forecast — The SK Hynix report is still a rumor. Watch whether external foundry revenue grows beyond $293 million. Without that, the Ohio story stays a story.
What to Watch on Next Week's Calendar
- September quadruple witching, Friday September 18. Index futures, index options, single-stock options, and futures options all expire on the same day, and the FTSE rebalance lands with them. Volume spikes and closing prints get distorted. Today's rebound came on a broad advance rather than on a few names, so the useful question on Friday is whether the chip and miner bids survive an expiration that forces mechanical selling.
- US August industrial production, Friday September 18, 9:15 a.m. ET (10:15 p.m. KST). The materials sector just rebounded +21 RS points and manufacturing-linked funds led the recovery list. A firm print supports that rotation. A weak one puts the cyclical bounce down to rates.
- Qualcomm Snapdragon Summit, September 22 to 24. Next-generation processor roadmaps get laid out here, and the event lands in the middle of a chip rebound that is still fragile — SOXX remains -2.31% over the past month even after today's +3.39%. Roadmap detail on on-device AI would give the semiconductor trade something more durable than a memory-pricing comment.
- US-China summit at the White House, Thursday September 24. President Xi Jinping's visit has AI development pace, AI security, semiconductors, and rare earths on the agenda. Every one of those touches a group in today's tables: chips on one side, critical minerals and silver miners on the other. This is the single largest scheduled risk to the sector map for the rest of the month.
#TempusAI #CarisLifeSciences #Intel #USStocks #StockMarket #NASDAQ #StockCharts


