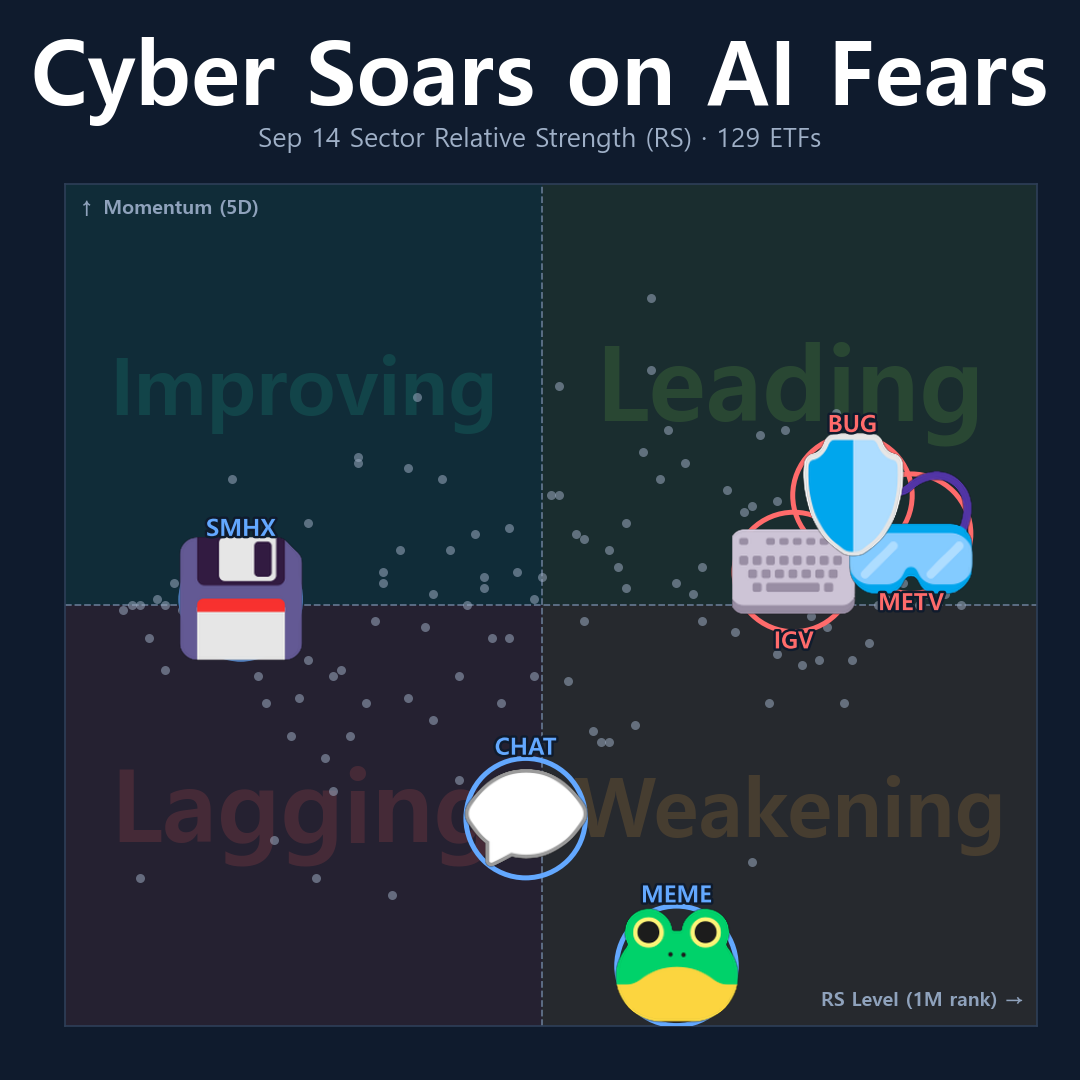
💡 Today's US market in three lines
① Today's three stocks: Okta · Salesforce · SM Energy — a cybersecurity platform, a cloud giant, and a Permian driller that each beat the S&P 500 on a session defined by a single essay.
② On September 14, the S&P 500 closed -0.48% at 7,619.98 and the Dow shed 152 points to 52,421.20. Of the 129 ETFs in our universe, 48 rose and 81 fell, with only 3 of the 11 sector SPDRs finishing green.
③ Anthropic CEO Dario Amodei's call to slow frontier AI development sent cybersecurity stocks surging and semiconductors crashing. CrowdStrike jumped 14%, while the VanEck Semiconductor ETF fell nearly 5%. One essay split the tech sector down the middle.
Today's Sector Relative Strength (RS)
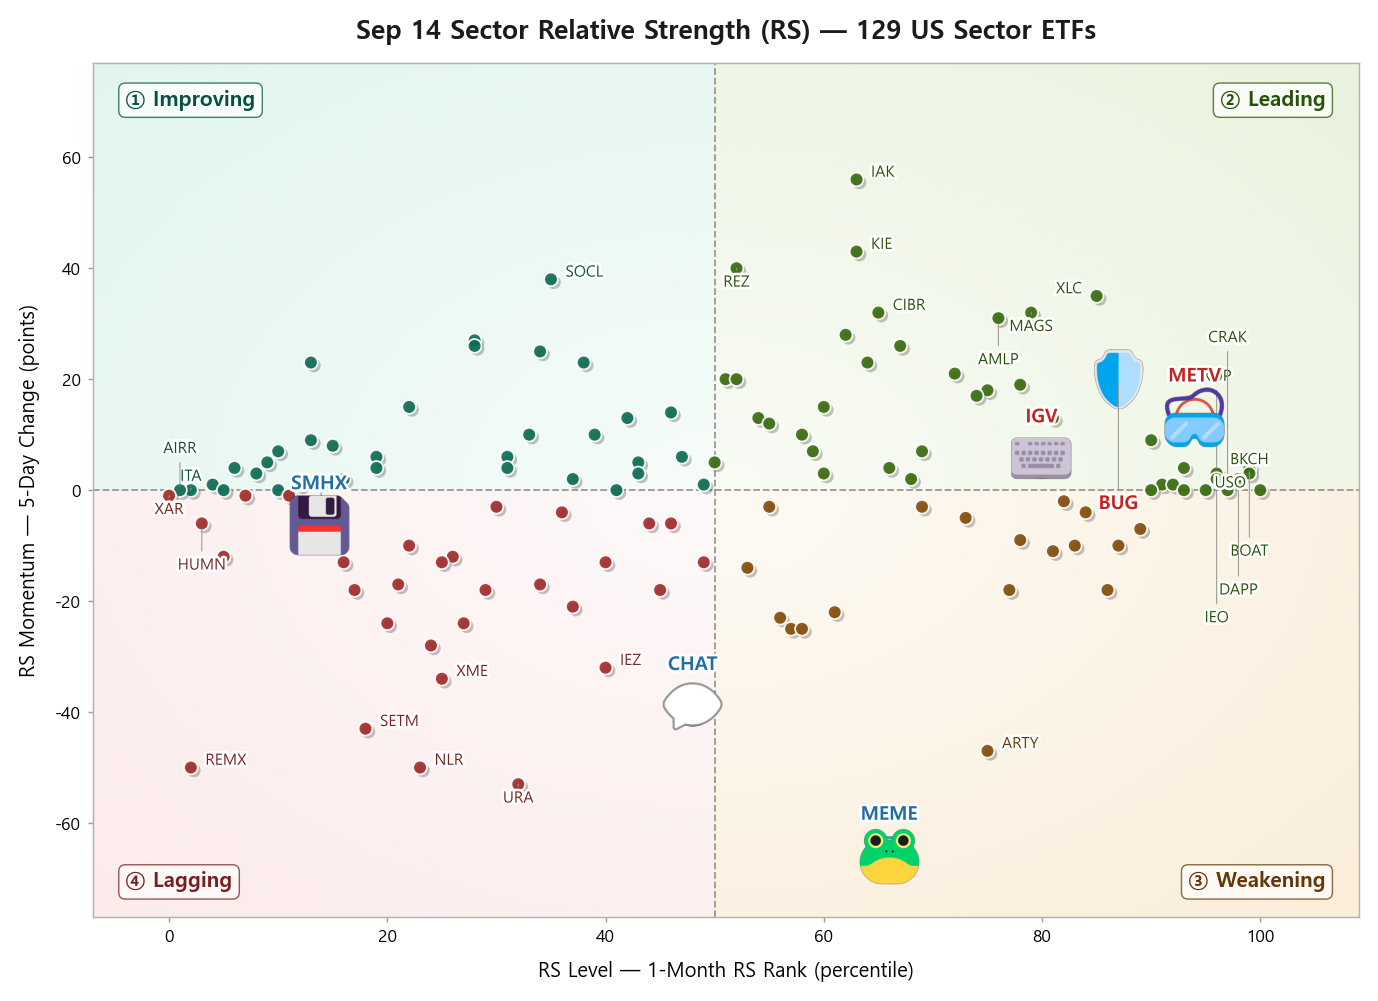
- A weekend essay did the work of a data release. On September 12, Anthropic's chief executive published a piece arguing that frontier models should be paced so safety research can catch up. CrowdStrike's CEO responded within hours, saying the answer was more security rather than less speed. Markets chose both narratives at once: cybersecurity stocks rallied and chipmakers sold off, as though the same paragraph was bullish for the companies that defend AI and bearish for the ones that build it.
- The S&P 500 closed -0.48% at 7,619.98, the Nasdaq -0.56% at 26,186.41, and the Dow -0.29% at 52,421.20. The surface looked like a flat day, but underneath, 81 of 129 ETFs fell. Only communication services, healthcare, and consumer staples among the eleven sector SPDRs managed to finish positive, and technology was the worst at -1.81%. The momentum factor gauge (SPMO) lost -2.80%, its heaviest single-day drop in weeks, while low volatility (USMV) and dividend (SCHD) both rose, a textbook defensive bid.
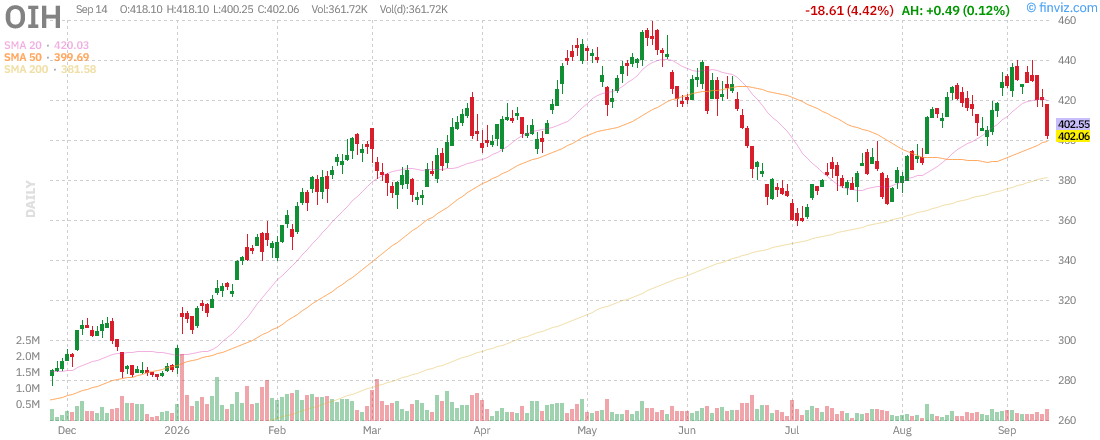
- Oil pulled back on the session. Brent crude settled at $104.61, down 2.8%, and WTI fell to $100.05, but the oil complex still owns the top of the RS table on its monthly gains. The retreat was enough to drag oil services (OIH) down -4.42% even though the commodity itself stayed above $100.
Today's Leading Sectors TOP 5
- Basis: top 5 by 1-month RS rank on the 'Sector RS (US)' sheet — 129-ETF universe, September 14, 2026. Daily moves are measured from Yahoo closing prices. Trend columns compare price to its 1-month, 1-quarter, and 1-year moving averages.
| ETF | 1-Day | RS Rank 1M | Short-Term | Mid-Term | Long-Term |
| United States Oil Fund (USO) | +1.14% | 100 | 🔺 | 🔺 | 🔺 |
| SonicShares Global Shipping (BOAT) | +0.71% | 99 | 🔺 | 🔺 | 🔺 |
| Global X Blockchain (BKCH) | +0.19% | 99 | 🔺 | 🔺 | 🔽 |
| VanEck Digital Transformation (DAPP) | +0.20% | 98 | 🔺 | 🔺 | 🔺 |
| VanEck Oil Refiners (CRAK) | -1.83% | 97 | 🔺 | 🔺 | 🔺 |
- The table is an energy and crypto board. Three oil names and two blockchain names account for every seat, and the order is built on monthly returns rather than anything that happened on Monday. USO is +25.3% for the month, an absolute outlier in a universe where the median sector ETF lost ground over the same stretch. The blockchain pair — BKCH at 99 and DAPP at 98 — held their ranks despite cooling this week; both are still up more than 11% for the month. Shipping rounds out the top at 99, riding the same freight-rate and commodity cycle that lifted the oil names.
Why They're Strong — Sector Issues
· Oil complex (USO · CRAK · IEO · XOP) — Four of the top seven RS seats belong to oil. WTI pulled back from $107 to $100 on the session, but the monthly print is still +25.3% for crude and +10.3% for refiners. The separation between commodity and services is the thing to watch: crude rose +1.14% while oil services (OIH) fell -4.42% and oil equipment (IEZ) lost -4.57%. That divergence says the commodity is pricing geopolitical supply risk while the equities are pricing the demand side, which just got an FOMC meeting staring at $100 oil.
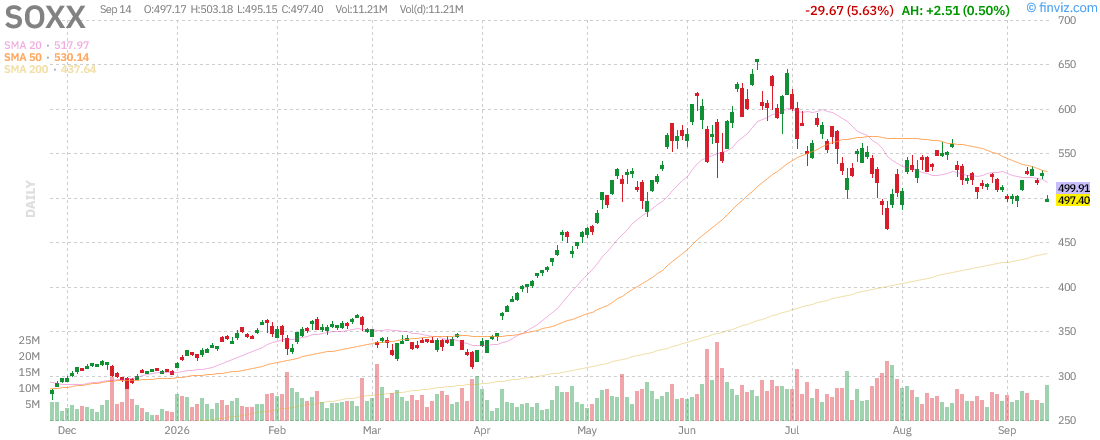
· Semiconductors — the collapse on the other side of the AI debate — The chip complex was already losing momentum before the weekend. Over five sessions, fabless semiconductors (SMHX) fell from RS 51 to 14, and broad semiconductors (SOXX) went from 57 to 13. On Monday, SMHX lost another -5.93% and SOXX -5.63%. Nvidia fell -3.4%, Broadcom -4.8%, Micron -5.2%. When Amodei said frontier models should slow down, the market heard reduced chip demand. The AI trade of 2025 is reversing position by position.
1-Month RS Trend
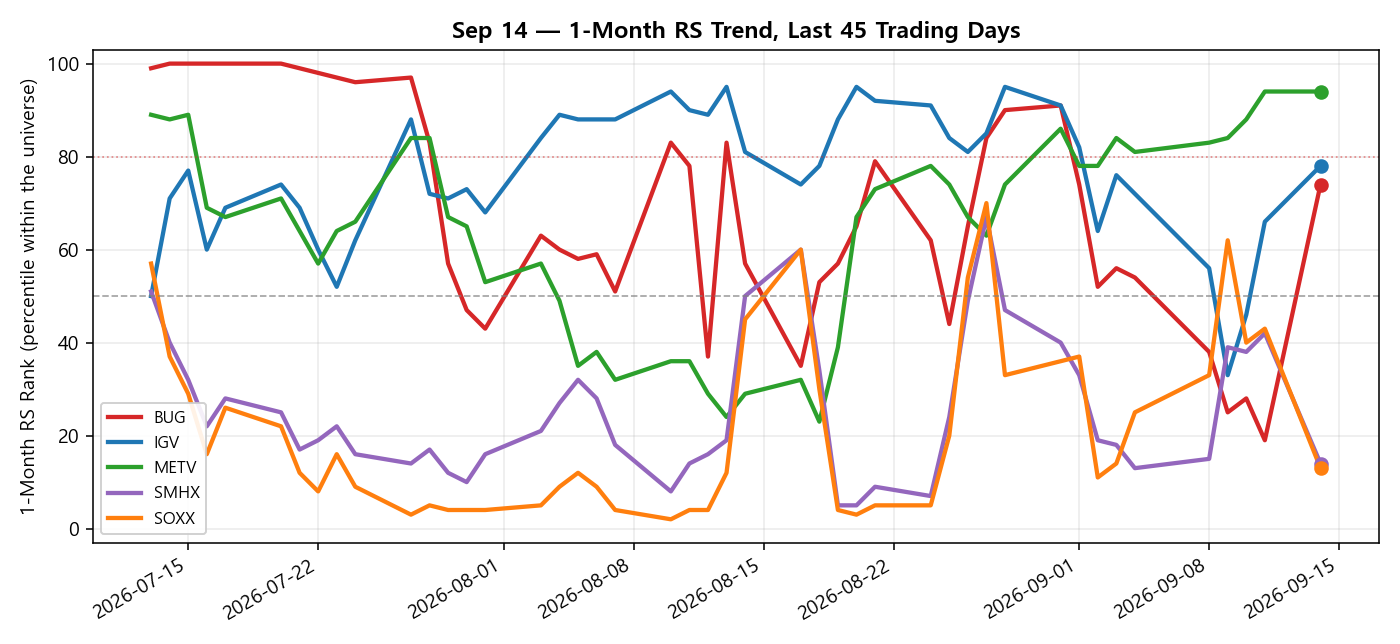
- Over 45 trading days, the trend chart captures a regime change. Cybersecurity (BUG) peaked at RS 100 in late July, fell to the mid-30s in early September, and is now bouncing to 74 — a wide swing that suggests the sector trades on headline cycles rather than steady demand. Software (IGV) climbed steadily from 50 to 78 with almost no drawdown, the quietest uptrend on the board. Metaverse (METV) pushed to 94, its highest reading in the observation window. The semiconductor pair — SMHX and SOXX — fell from the 50s to 13–14 and show no sign of leveling off.
RS Breakdown Warnings (big 5-day drops)
· Meme stocks fell -66 points in five trading days, from 78 to 12, the largest five-day decline in the universe. Uranium lost -53 points, nuclear power -50, and rare earths -50. These are the marginal-capital trades that get liquidated first when sentiment turns. The AI adjacent complex continued lower: ARTY (future AI) fell -47, SETM (critical minerals) -43, and oil equipment (IEZ) -32.
· The damage is not confined to one sector. Metals, mining, nuclear, AI infrastructure, and meme stocks all broke down in the same week. When that many different themes sell off together, the common cause is positioning rather than any single catalyst.
RS Rebound Signals (sharp bounces off the bottom)
· Insurance rallied +56 points in five sessions, from 21 to 77, the largest rebound in the universe. SPDR Insurance (KIE) followed at +43, residential REITs (REZ) at +40, and social media (SOCL) at +38. These are the sectors that were priced for rising rates and have started to reprice as the hiking narrative cracked.
· Cybersecurity appeared here too. First Trust Cybersecurity (CIBR) rebounded +32 points and iShares Cybersecurity (IHAK) +28, both starting from the low 20s–30s. Retail (XRT) added +27 and consumer discretionary (XLY) +26. The rebound list is heavy on defensive and consumer sectors, which is the mirror image of the breakdown list.
Today's Top Rising Sectors TOP 5 (by 1-day %)
- Basis: top 5 by September 14 closing move — 48 of 129 rose on the day. RS ranks from the 'Sector RS (US)' sheet.
| ETF | 1-Day | RS Rank 1M | Short-Term | Mid-Term | Long-Term |
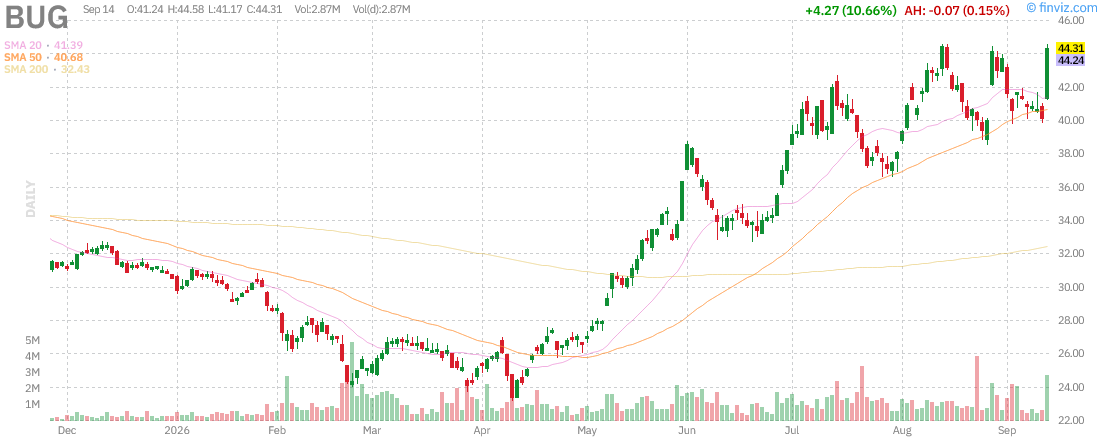
| Global X Cybersecurity (BUG) | +10.66% | 87 | 🔺 | 🔺 | 🔺 |
| iShares Cybersecurity (IHAK) | +7.78% | 62 | 🔺 | 🔺 | 🔺 |
| WisdomTree Cloud Computing (WCLD) | +6.37% | 86 | 🔺 | 🔺 | 🔺 |
| First Trust Cybersecurity (CIBR) | +5.99% | 65 | 🔺 | 🔺 | 🔺 |
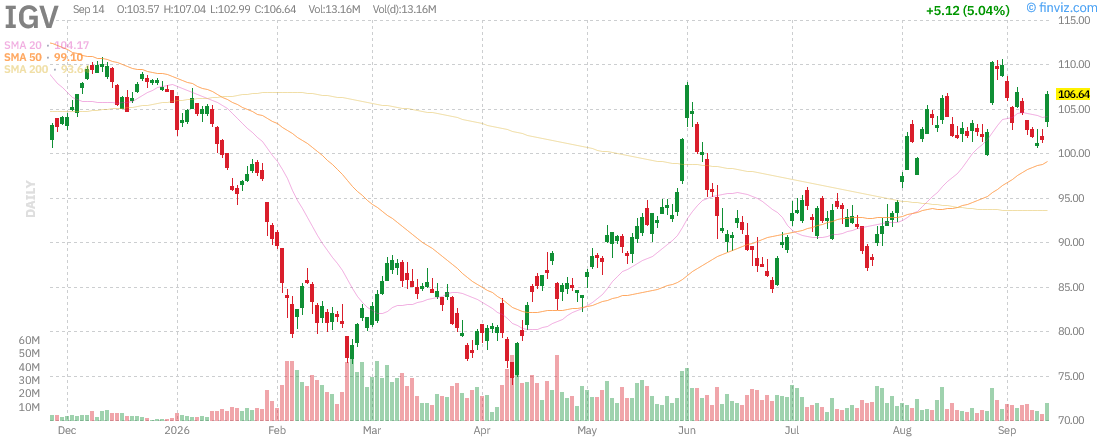
| iShares Software (IGV) | +5.04% | 80 | 🔺 | 🔺 | 🔺 |
- Three of the five are cybersecurity, and the other two are cloud and software. This is the AI-safety trade in concentrated form: investors bought the companies that protect systems and sold the ones that build them. Note the RS ranks: BUG is at 87 and WCLD at 86, both above the median but not at the top of the table. They were already improving before Monday, and the Amodei essay accelerated a trend that had started weeks earlier.
Why They Rose — Sector Issues
· Cybersecurity (BUG · IHAK · CIBR) — Up +10.66% on the headline alone. Dario Amodei published a 4,000-word argument for voluntary deceleration of frontier AI, citing systemic cybersecurity risks. CrowdStrike responded by calling for more security investment rather than slower models. The market read both positions as demand for the same products: CrowdStrike surged 14%, Zscaler 14%, Palo Alto 13%, and Okta 12%. The move is wide enough to be a sector event rather than a single-stock reaction.
· Software and cloud (IGV · WCLD · CLOU) — Software rose +5.04%, cloud +6.37%, and Global X Cloud +4.50%. IGV has climbed from RS 50 to 78 over 45 days without a significant drawdown, making it the steadiest trend on the board. Salesforce's strong August quarter anchored the group, and Monday's AI safety narrative added a secondary bid: if frontier models slow down, the value of existing enterprise software installed bases goes up. Cloud held an RS of 86 and sits above all three moving averages.
Leading Sectors: Cybersecurity, Software, Oil
- ① The session had one driver and it was an essay. Anthropic's CEO argued for pacing AI development; CrowdStrike's CEO argued for securing it faster. Markets decided that both arguments pointed at the same trade — buy the companies that defend AI-powered systems and sell the ones that build the hardware those systems run on. Cybersecurity gained +10.66% while semiconductors lost -5.63%. That is the widest single-day spread between two tech subsectors this year.
- ② Oil still holds the RS table despite Monday's pullback. USO at 100, CRAK at 97, IEO at 96, XOP at 96 — all built on a month where WTI went from $80 to $100. The fact that oil services (OIH -4.42%) diverged from crude on the same day is a warning that the equities are more fragile than the commodity. If the FOMC on Wednesday guides hawkish with oil at $100, the services gap could widen.
- ③ The rebound list is insurance and consumer, not growth. IAK gained +56 RS points in five days, KIE +43, REZ +40. These are the rate-sensitive laggards that come back first when the tightening narrative cracks. The breakdown list is meme stocks, uranium, rare earths, and AI infrastructure — the speculative complex that got too far ahead of the cycle. Both rotations point at the same conclusion: the market is repricing for a slower, more defensive environment.
- ④ The last report was dated September 11. Its three picks, measured from that close to Monday: Dell Technologies -5.82%, Skyworks Solutions -10.29%, and Valero Energy -1.91%. The S&P 500 returned -0.45% over the same stretch, so all three underperformed. Dell and Skyworks were caught in the semiconductor selloff that accelerated through the session, and Valero fell with the broader oil equities pullback. Recorded as is.
Today's Three Stocks — Okta · Salesforce · SM Energy Stock Forecast
- Selection: from the 1,187 stocks held by the universe's ETFs — RS 1D≥60 & 5D≥75 & 1M≥85, with all three moving averages aligned (▲▲▲)
Okta (OKTA) — 1-Month RS 98: Cybersecurity Identity Platform at a New 52-Week High

| RS 1D | RS 5D | RS 1M | 1M Return | Held By |
| 99 | 98 | 98 | +20.3% | Global X Cybersecurity · iShares Cybersecurity · First Trust Cybersecurity |
- Up +11.98% to $186.45, hitting a new 52-week high and carrying a 7.5% weight in the cybersecurity ETF that led the market. Okta is the largest pure-play identity platform in the universe. Its Q2 fiscal 2027 revenue landed at $805 million, up 11% year over year, with total current remaining performance obligations of $2.585 billion. Non-GAAP operating margin was in the low 20s, well above the company's historical breakeven. The AI safety narrative lands directly on Okta's product: if companies need to secure access to AI agents and models, identity verification is the first gate. The Okta stock forecast rests on whether this headline-driven demand converts into pipeline — the company needs to show faster net new customer additions in the next quarter to justify the multiple, not just faster trading volume in the stock.
Salesforce (CRM) — 1-Month RS 99: Agentforce Crossed $1.5B ARR
| RS 1D | RS 5D | RS 1M | 1M Return | Held By |
| 94 | 75 | 99 | +28.8% | iShares Software · First Trust Dow Jones Internet · Global X Cloud Computing |
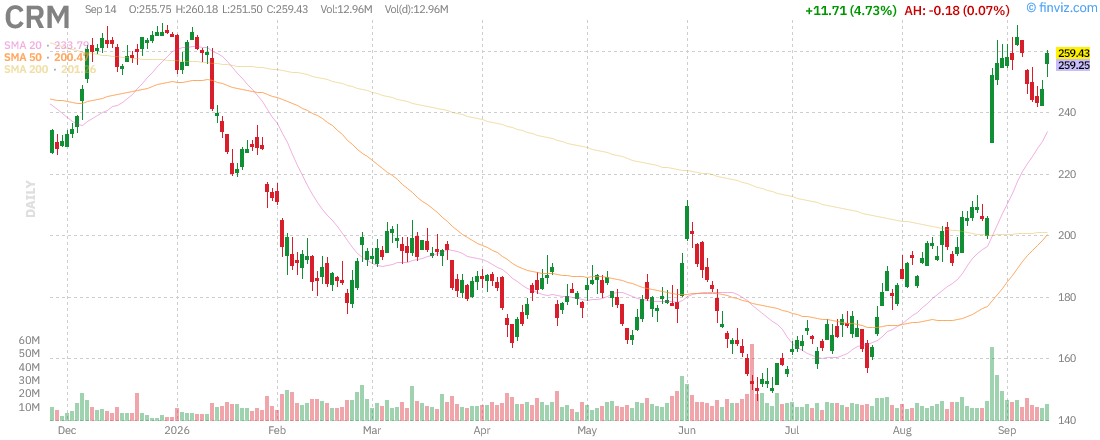
- Up +4.73% to $259.43, adding to a +28.8% month that has pushed the 1-month RS to 99. Salesforce reported Q2 FY27 on August 26 and beat on every line: revenue of $11.35 billion, up 10.8%, and non-GAAP EPS of $5.90 against a $3.27 consensus, an 80% beat. The headline was Agentforce reaching $1.5 billion in annual recurring revenue with triple-digit booking growth. Management disclosed a partnership with Anthropic — the same company whose CEO's essay drove Monday's session. The Salesforce stock forecast depends on whether Agentforce bookings convert to consumption revenue in the fiscal third quarter. The 5-day RS of 75 is the weakest link; the stock has been rising on the monthly but not accelerating on the weekly.
SM Energy (SM) — 1-Month RS 98: Permian Basin Driller in a $100-Oil World
| RS 1D | RS 5D | RS 1M | 1M Return | Held By |
| 86 | 98 | 98 | +20.4% | First Trust Natural Gas · SPDR Oil and Gas Exploration · iShares Oil and Gas Exploration |
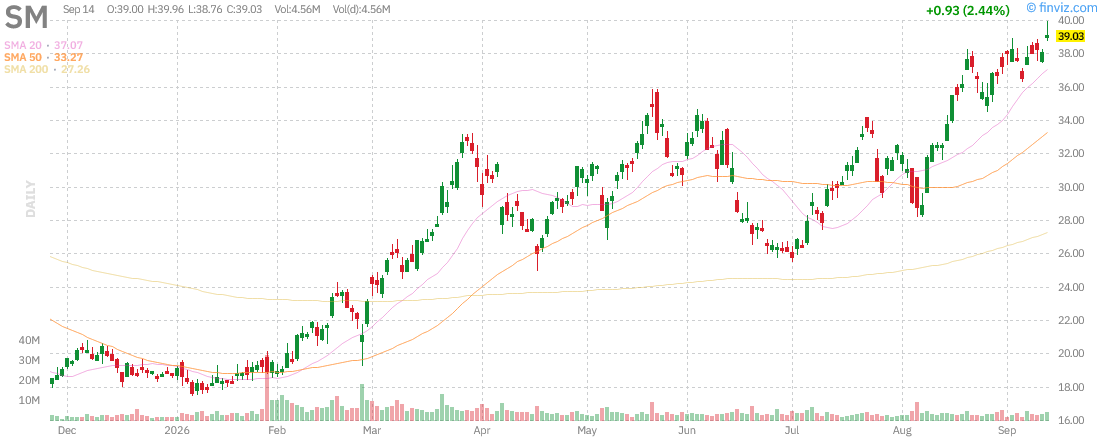
- Up +2.44% to $39.03, quietly holding gains while the broader oil equity complex pulled back. SM Energy operates in the Midland Basin, South Texas, and Uinta Basin, and at $100 WTI, every barrel produced generates cash flow well above its breakeven in the mid-$40s. Q2 2026 revenue came in at approximately $2.5 billion on a semi-annual basis, with net income of $1.07 billion. UBS raised its price target to $48 from $36 on Monday. The SM Energy stock forecast is a direct function of the oil price: the company has no diversification, no hedging complexity, and no pipeline bottleneck. If WTI holds above $90, the current production profile generates more than $15 per share in annual free cash flow. The risk is the same simplicity — a retreat below $80 removes the entire margin of safety.
Okta · Salesforce · SM Energy Stock Forecast Checkpoints
· Okta stock forecast — The 12% session was sector sympathy, not a company event. Watch whether net new customer additions accelerate in the Q3 FY27 print. The stock moved on a narrative; it needs to move on a number next.
· Salesforce stock forecast — Agentforce at $1.5B ARR is the thesis. Watch whether consumption revenue growth reaccelerates in the fiscal Q3 guide. The 5D RS of 75 suggests the market is not yet fully committed to the acceleration story.
· SM Energy stock forecast — This is an oil bet, nothing else. Watch whether WTI holds above $90 through the FOMC and quarterly expiration this week. Every dollar below $90 shrinks the free cash flow case by roughly $1.50 per share.
What to Watch on Next Week's Calendar
- FOMC rate decision, Wednesday September 17, 3:00 a.m. KST (Tuesday 2:00 p.m. ET). CME FedWatch prices a 25-basis-point hike at 85–87% probability. This is the dominant event of the week. Oil at $100 and services ISM at 55.4 give the hawks ammunition, while the AI safety debate and the semiconductor selloff give the doves a growth-risk argument. The Summary of Economic Projections will matter as much as the rate itself — if the dot plot signals more hikes beyond September, every rate-sensitive sector on the rebound list reverses.
- CLARITY Act cloture vote, Monday September 15, 2:15 p.m. ET (Tuesday 3:15 a.m. KST). The stablecoin regulatory bill needs 60 Senate votes to advance. Failure effectively kills the legislation this session. Blockchain ETFs sit at RS 98–99; a failed vote could unwind a month of positioning in BKCH, DAPP, and their constituent stocks including Circle.
- Quadruple witching, Friday September 18. Quarterly options and futures expiration. With the widest tech-sector dispersion in months — cybersecurity up 10.66% vs semiconductors down 5.63% — the pinning effects around Friday's expiration could either lock these extremes in or force a violent mean reversion. Position sizing matters more than direction this week.
- AI Infrastructure Summit, Monday–Wednesday September 15–17. Alphabet, Amazon, Meta, Nvidia, and Tesla are all participating. Given that an essay from one AI CEO moved markets by 10% in a single session, any statement from another could do the same. The summit is not a data event, but it is a headline-generation machine at a moment when headlines are what the market is trading.
#Okta #Salesforce #SMEnergy #USStocks #StockMarket #NASDAQ #StockCharts


